
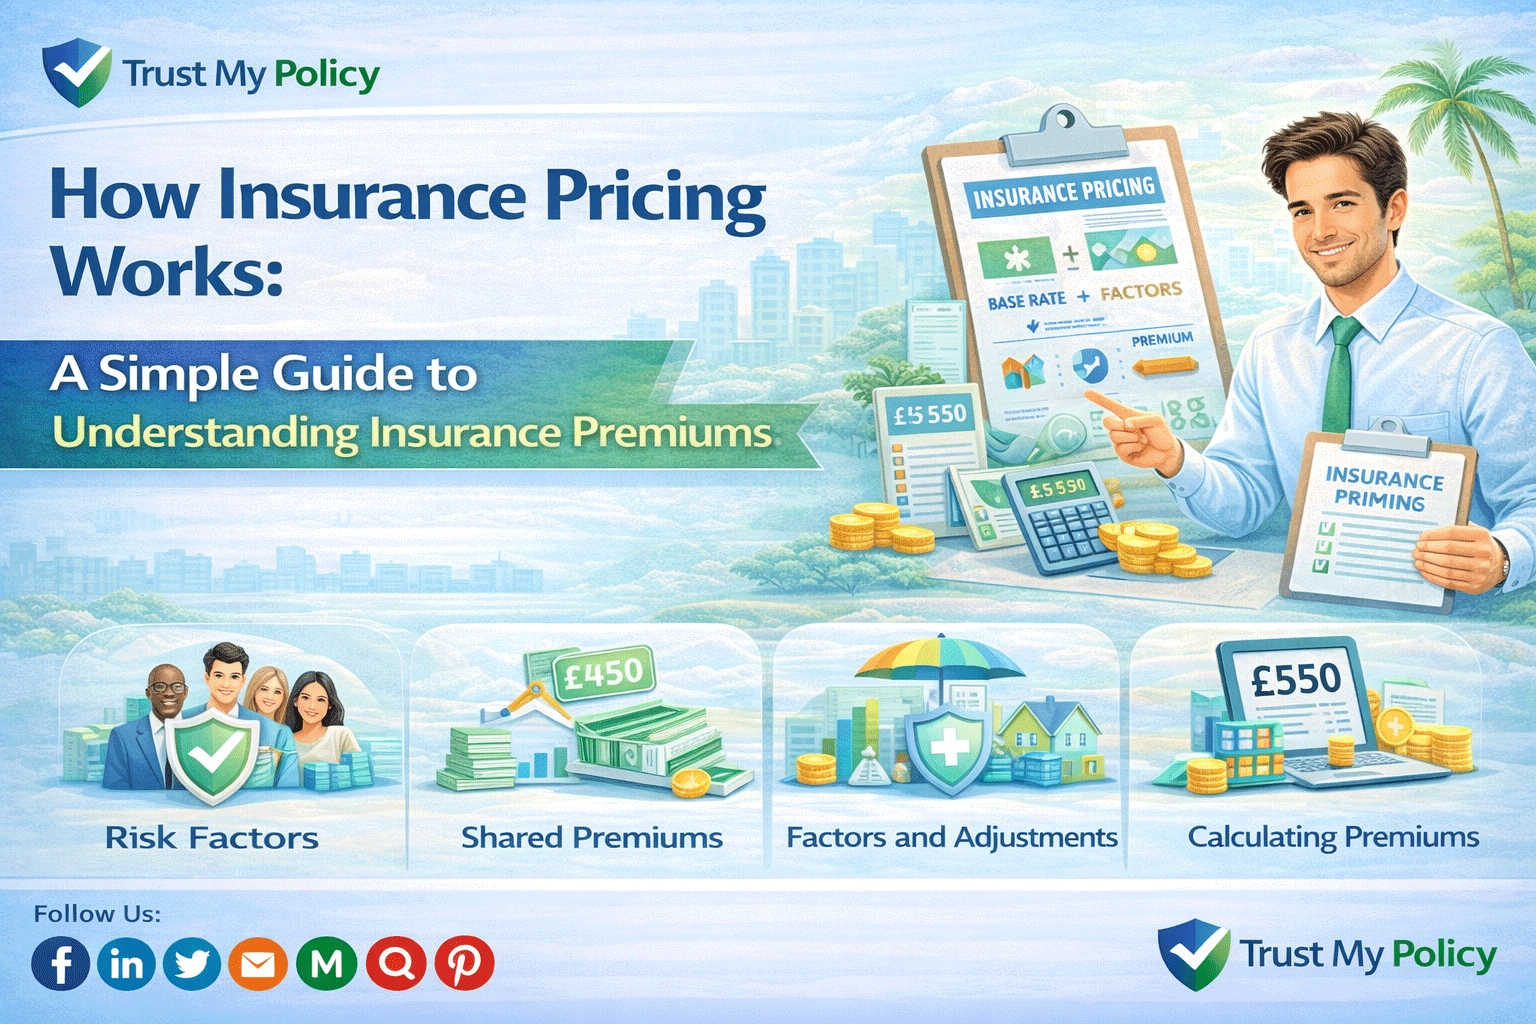
Insurance pricing starts with a base rate calculated from historical claims data, which is then adjusted using rating factors specific to you, such as age, location, and claims history. In the US, most rate changes must be filed with and approved by state insurance regulators before taking effect. In the UK, the Financial Conduct Authority oversees fair pricing practices, though there’s no line-by-line rate filing system like in the US.
Carlos Reyes, 47, manages a fleet of delivery vans in Houston and asked his broker why his renewal increase had to be “filed” with the state before it took effect. He’d never realized insurers can’t just raise prices overnight — every rate change for regulated lines of insurance goes through a formal approval process most policyholders never see.
How Insurance Pricing Works in 2026 starts with a base rate built from years of claims data, gets adjusted by rating factors specific to you, and then must be filed with and often approved by state insurance regulators in the US or reviewed under Financial Conduct Authority rules in the UK before it reaches your quote. This guide breaks down the entire pricing pipeline, from the actuary’s spreadsheet to the number on your renewal notice.
This article covers how base rates are built, how rating factors adjust your price, the regulatory approval process behind rate changes, real scenarios showing the pipeline in action, and what this means for shopping smarter. By the end, you’ll understand the full pricing process, not just your own quote.
| Feature | Details |
| What it is | The full pricing pipeline from base rate calculation to your final quoted premium |
| Who it affects | Every policyholder, since base rates and regulatory approval shape your final price |
| Core building blocks | Base rate, rating factors, expense load, profit margin |
| Regulatory role (US) | State insurance departments review and approve most rate filings |
| Regulatory role (UK) | Financial Conduct Authority oversees fair pricing conduct, not individual rate filings |
| Key benefit | Ensures pricing is grounded in data and subject to regulatory oversight |
| Key limitation | The approval process can mean rate changes lag behind real-time claims trends |
Picture pricing a policy like building a custom price quote for a renovation — the contractor starts with a base cost per square foot, then adds or subtracts based on your specific materials, location, and timeline. Insurance pricing works the same way, just using statistical risk factors instead of materials.
The insurance pricing pipeline starts with a base rate, calculated from years of aggregated claims data for a specific line of business. That base rate is then adjusted using rating factors specific to the individual applicant, plus a loading for administrative expenses and profit margin. In the US, the resulting rate structure typically must be filed with, and often approved by, state insurance regulators before insurers can use it. Anyone curious why their renewal didn’t change the moment they expected, or why pricing varies by region, needs to understand this full pipeline.
| Criteria | US Rate Filing System | UK Pricing Oversight |
| Approval process | Insurers file specific rate changes with each state’s insurance department | No line-by-line rate filing; FCA oversees fair treatment of customers broadly |
| Speed of change | Can be slower due to formal regulatory review | Can be faster, since individual rates aren’t pre-approved |
| Transparency to consumers | Rate filings are often public record in many states | Less individual rate transparency, but strong conduct-focused consumer protections |
| Pros | Provides a formal check against excessive or discriminatory rates | Allows insurers more pricing flexibility and speed |
| Cons | Rate changes can lag behind real-time claims trends | Relies more heavily on broader market competition to keep pricing fair |
We recommend US readers check whether their state publishes rate filings publicly, and UK readers focus on comparing quotes directly, since pricing oversight works differently in each system.
Scenario 1: Carlos, 47, fleet manager in Houston. Carlos learned his insurer’s proposed 18% rate increase had to be filed with and approved by the Texas Department of Insurance before it applied to his fleet policy. Verdict: regulated rate changes go through formal review, even for commercial lines. Action: Carlos requested a copy of the approved rate filing to understand exactly which factors drove the increase.
Scenario 2: A UK driver comparing quotes after a market-wide price rise. Without a public rate filing system to check, she relied on comparing multiple insurers directly through a comparison site instead. Verdict: UK pricing oversight relies more on market competition than formal rate approval. Action: she compared five UK insurers and found a 12% lower quote from a competitor.
Scenario 3: A US homeowner in a wildfire-prone California county. Her insurer’s proposed regional rate increase took over a year to gain regulatory approval, during which her premium stayed temporarily unchanged despite rising regional claims costs. Verdict: the rate filing process can create a lag between real-world claims trends and approved pricing. Action: she used that year to invest in defensible space landscaping before the new rate took effect.
Scenario 4: A small US auto insurer entering a new state market. It had to file its entire base rate structure and rating factor methodology with that state’s insurance department before writing any policies. Verdict: even new market entrants must clear the same regulatory pricing hurdles as established insurers. Action: the insurer used a conservative initial rate filing to ensure smooth regulatory approval.
| Pros | Cons |
| US rate filing systems provide a formal check against excessive pricing. | The approval process can delay rate adjustments behind real-world claims trends. |
| Base rates ensure pricing is grounded in years of aggregated data, not guesswork. | Building blocks like expense loads and profit margins aren’t always visible to consumers. |
| UK market-based pricing allows for faster competitive rate changes. | UK consumers have less direct visibility into how a specific rate was calculated. |
| Regulatory oversight in both countries aims to prevent discriminatory pricing practices. | Comparing rate structures across insurers and states/countries can be genuinely complex. |
| Public rate filings in some US states offer real transparency for curious consumers. | Not all US states make rate filings easily accessible to the public. |
⚠️ WARNING: Never assume a large, sudden premium increase is automatically improper just because it feels steep. In the US, it’s worth checking whether the increase reflects an approved, regulator-reviewed rate filing before assuming something irregular happened.
| Your Situation | Our Recommendation |
| You received a large premium increase in the US | Yes — check your state insurance department for the related rate filing |
| You’re a UK policyholder facing a market-wide price rise | Yes — compare quotes directly across multiple insurers rather than expecting a filing record |
| You want to understand exactly how your rate was built | Yes — ask your insurer for a breakdown of base rate and rating factors |
| You’re a small business shopping for commercial insurance | Yes — ask whether the insurer’s rate structure has been recently filed or revised |
| You suspect a rate increase may be discriminatory or improper | Yes — file a complaint with your state insurance department or the FCA |
| You’re comparing US and UK pricing systems out of general curiosity | Yes — understand that the US uses formal rate filing while the UK relies more on market competition |
| Your renewal price didn’t change despite news of industry-wide increases | No immediate action — but expect a filed rate change to apply at a future renewal |
💡 TIP: The single golden rule for understanding insurance pricing: your premium isn’t a single arbitrary number — it’s built from a base rate, adjusted by rating factors, and in the US, typically reviewed by a regulator before it ever reaches your quote.
| Scenario | Pricing Component | Notes |
| Base rate for a standard auto policy | $600–$900/year before adjustments | Reflects average claims cost across the entire line of business |
| Rating factor adjustment for a young driver | +20%–50% above base rate | Reflects elevated statistical risk for that age group |
| Rating factor adjustment for a clean 10-year record | -10%–20% below base rate | Reflects lower statistical risk |
| Expense load added to base rate | +10%–20% | Covers insurer operating and administrative costs |
| Profit margin added to base rate | +3%–8% | Varies by insurer and regulatory environment |
| US rate filing approval timeline | Weeks to over a year | Varies significantly by state and complexity of the filing |
| UK market-driven price adjustment | Can apply within weeks | Reflects faster competitive repricing without formal filing approval |
Your state insurance department (US) — Many states publish rate filings publicly, allowing you to review the actual data behind a rate change. Cost range: free to access. Best for: US consumers wanting to verify a specific rate increase. Rating: government regulatory body.
NAIC (National Association of Insurance Commissioners) — Offers consumer guidance on how rate regulation works across different US states. Cost range: free public resource. Best for: US consumers researching the regulatory pricing process. Rating: regulatory standards body.
Financial Conduct Authority (UK) — Publishes guidance on fair pricing conduct rules for UK insurers. Cost range: free to consult. Best for: UK consumers wanting to understand pricing oversight. Rating: government regulatory body.
Independent insurance brokers — Brokers can explain how a specific insurer’s rating factors are likely affecting your quote. Cost range: typically free for the consumer. Best for: anyone wanting a plain-language breakdown of their own quote. Rating: varies by broker, check state or FCA licensing.
Society of Actuaries (US) and Institute and Faculty of Actuaries (UK) — Professional bodies offering public resources on actuarial pricing methodology. Cost range: free public resources available. Best for: readers wanting deeper technical understanding. Rating: professional actuarial bodies.
We recommend your state insurance department or the Financial Conduct Authority as best overall starting point because both offer free, regulator-level transparency into how pricing oversight actually works in your country.
Insurance pricing starts with a base rate built from historical claims data, which is then adjusted using individual rating factors, expense loads, and profit margin, often subject to regulatory review before use.
In the US, yes, in most cases. Insurers typically must file rate changes with state insurance departments, which review and approve them before they can be used.
No. The UK doesn’t use a line-by-line rate filing system; instead, the Financial Conduct Authority oversees fair pricing conduct more broadly, relying on market competition to keep pricing in check.
A base rate is the starting price calculated from aggregated historical claims data for a specific line of insurance, before any individual rating factors are applied.
In the US, this can reflect the regulatory approval timeline for a rate filing, which can take anywhere from a few weeks to over a year depending on the state and complexity.
In many US states, yes. Rate filings are often public record and can be requested or viewed through your state insurance department’s website.
The expense load covers an insurer’s administrative costs, including claims processing, customer service, marketing, and reinsurance costs.
Not exactly less regulated, just differently regulated. The UK focuses on fair customer treatment and conduct rules rather than approving individual rate filings.
Different insurers use different historical data and actuarial models, leading to genuinely different rating factor weightings even for similar risks.
Yes, if you believe a rate change seems improper or inconsistent with regulations, filing a complaint with your state insurance department or the Financial Conduct Authority is a legitimate next step.
This guide reflects the latest 2026 insurance data.
This article is for informational purposes only. Always consult a licensed insurance professional before making coverage decisions. Trust My Policy does not sell insurance products or represent any insurer.

Jagadeesh Gutha is the founder of TrustMyPolicy.com, an independent insurance information platform covering life, health, car, home, and business insurance for US and UK readers. He researches insurance products, policy structures, and consumer rights to help everyday people make informed coverage decisions without the jargon. All content on TrustMyPolicy is independently researched, fact-checked, and written to educate — not to sell.

Insurance Guides for UK, USA & Worldwide We are not an insurer or broker.
Reader Comments (1)
[…] main insurance pricing models are risk-based pricing, which sets your premium according to your individual risk factors, […]