
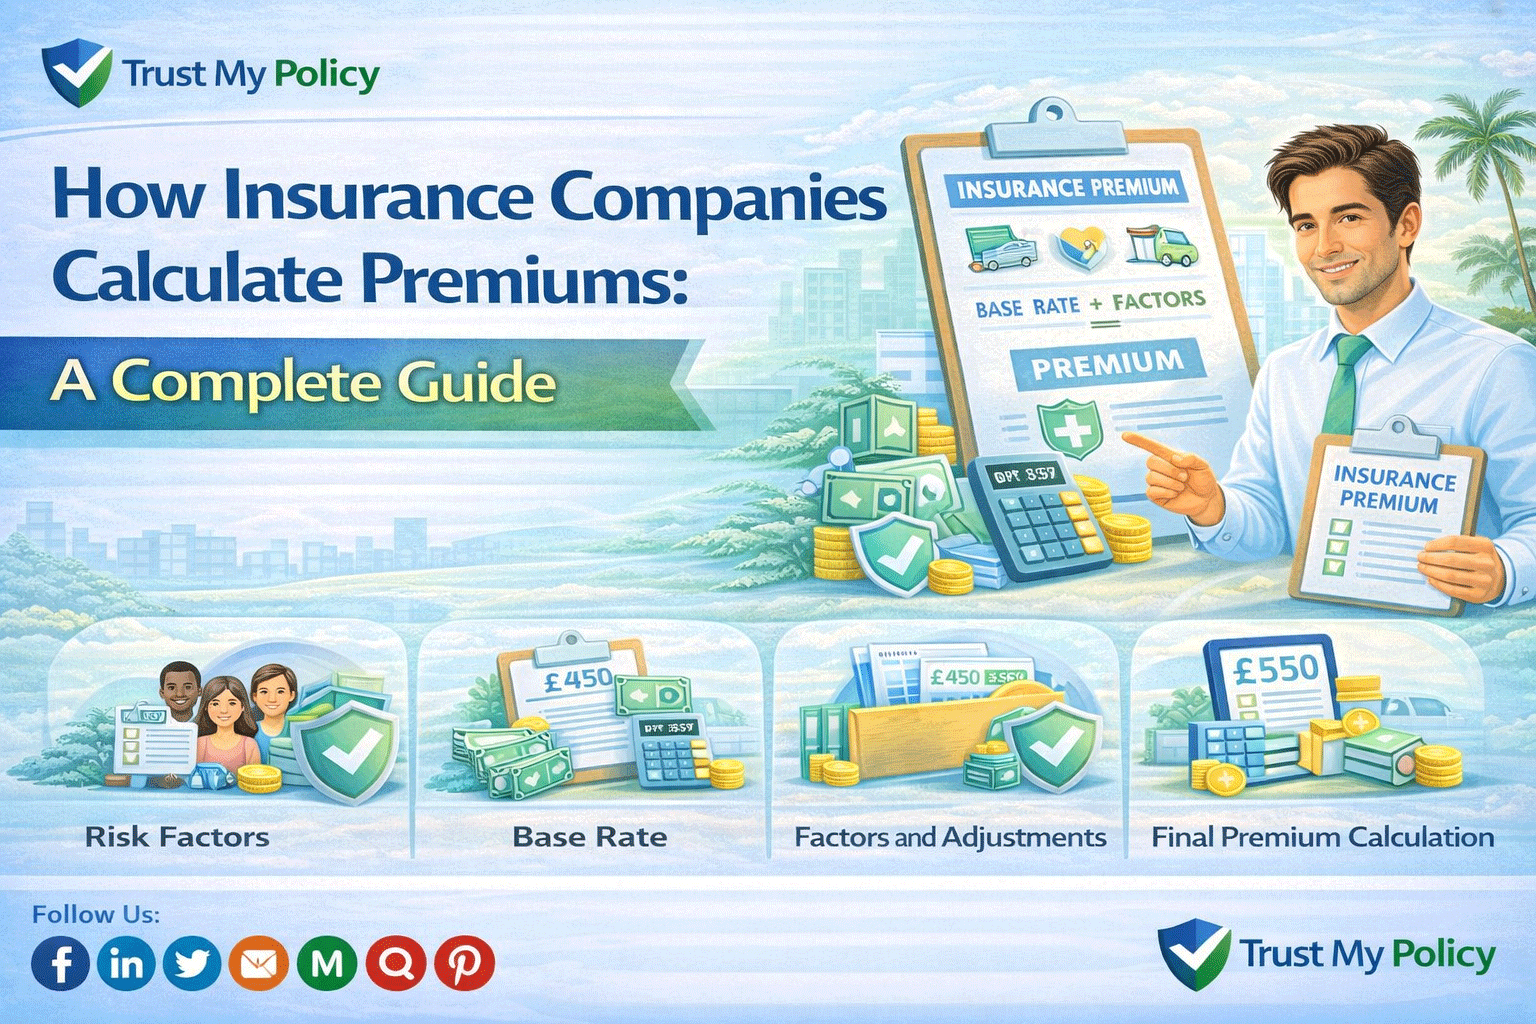
Insurance companies calculate premiums using a base rate multiplied by individual rating factors, such as age, location, and claims history, then add expense loads and profit margin. For example, a $900 base auto rate might be multiplied by a 1.2 factor for a higher-risk age group and a 1.1 factor for a higher-risk ZIP code, resulting in a final premium around $1,188 before expense and profit adjustments.
Erin Walsh, 34, asked her auto insurer for an exact breakdown of her $112 monthly premium after a renewal increase in Phoenix. To her surprise, the agent walked her through an actual formula: a base rate, multiplied by several specific factors for her age, location, and vehicle, plus a flat expense charge. Seeing the real math made the number feel far less arbitrary.
How Insurance Companies Calculate Premiums in 2026 follows a consistent structure: start with a base rate for the coverage type, multiply it by a series of individual rating factors specific to you, then add expense loads and profit margin. This guide walks through the exact formula insurers use, with a real worked example showing how each factor moves the final number.
This article covers the core premium calculation formula, what each rating factor actually does to the math, a full worked example, real scenarios, and what this means for shopping smarter. By the end, you’ll be able to roughly estimate how your own factors affect your premium.
| Feature | Details |
| What it is | The specific formula insurers use to turn a base rate into your final premium |
| Who it applies to | Auto, home, health, and life insurance applicants and policyholders |
| Core formula | Base rate × rating factors + expense load + profit margin |
| Common rating factors | Age, location, claims history, coverage limits, vehicle or property type |
| Key benefit | Demystifies your premium by showing the actual math behind the number |
| Key limitation | Exact formulas and factor weightings vary by insurer and aren’t usually public |
| Regulator | State insurance departments (US); Financial Conduct Authority (UK) |
Think of your premium calculation like a recipe with a base ingredient and several multipliers. The base rate is the flour — the foundation everyone starts with for that type of coverage. Then specific multipliers, like your age or location, adjust the recipe up or down based on your particular ingredients.
The core premium formula insurers use is: base rate, multiplied by a series of individual rating factors specific to the applicant, plus an expense load for administrative costs, plus a profit margin. Each rating factor is typically expressed as a multiplier — a number above 1.0 increases the premium, while a number below 1.0 decreases it. Anyone wanting to understand exactly why their premium is the number it is needs to see this formula in action.
| Step | Calculation | Running Total |
| Base rate for standard auto liability coverage | $900/year | $900 |
| Age rating factor (driver age 22, higher risk) | × 1.35 | $1,215 |
| Location rating factor (higher-traffic ZIP code) | × 1.10 | $1,337 |
| Claims history factor (one minor claim in 3 years) | × 1.15 | $1,537 |
| Vehicle type factor (mid-size sedan, average risk) | × 1.00 | $1,537 |
| Expense load (covers administrative costs) | + 15% | $1,768 |
| Profit margin | + 5% | $1,856 |
| Final annual premium | $1,856 (~$155/month) |
This is a simplified illustrative example. Real insurer formulas often include dozens of rating factors and proprietary weightings that aren’t published publicly.
| Criteria | Factors That Increase the Multiplier | Factors That Decrease the Multiplier |
| Age (auto insurance) | Younger or very senior drivers | Middle-aged drivers with experience |
| Location | High-traffic, high-crime, or high-weather-risk areas | Lower-risk neighborhoods and regions |
| Claims history | Recent claims or violations | Long claims-free history |
| Coverage choices | Lower deductible, higher coverage limits | Higher deductible, bundled policies |
| Pros of understanding this | Helps you anticipate which factors are working against you | Helps you actively target factors you can realistically improve |
We recommend asking your insurer directly which specific multipliers apply to you for most readers, since this is the clearest way to understand your own calculated premium.
Scenario 1: Erin, 34, driver in Phoenix. Erin’s broker walked her through her actual base rate and three specific multipliers, showing exactly how her $112 monthly premium was calculated. Verdict: seeing the real formula made an abstract number concrete and explainable. Action: Erin asked which factor she could realistically improve and learned a defensive driving course could lower her claims-related multiplier.
Scenario 2: A 24-year-old driver in Manchester with a brand-new car. His insurer applied a higher vehicle-type multiplier due to the car’s higher repair cost, significantly raising his calculated premium above a similar driver with an older car. Verdict: vehicle type is a real, separate multiplier in the formula, not just age or location. Action: he compared insuring a slightly older, cheaper-to-repair model instead.
Scenario 3: A homeowner in Florida whose base rate rose after a regional hurricane season. Even with no personal claims, her base rate for that coverage type increased, raising her calculated premium across the board. Verdict: base rate changes affect everyone in a region, regardless of individual rating factors. Action: she compared quotes from insurers using a different base rate methodology for her specific region.
Scenario 4: A small business in Texas comparing two insurers’ calculated premiums for identical coverage. One insurer’s higher expense load resulted in a noticeably higher final premium despite a similar base rate and rating factors. Verdict: expense load and profit margin differences between insurers can meaningfully affect the final number. Action: the business chose the insurer with the lower expense load for equivalent coverage.
| Pros | Cons |
| The formula structure makes pricing explainable and grounded in data. | Exact multiplier values and weightings aren’t usually published publicly. |
| Understanding the formula helps identify which factors you can actually improve. | Comparing formulas across insurers is difficult without seeing the actual math. |
| Multiplier-based pricing allows fine-tuned risk-based adjustments. | Small changes in multiple factors can compound into a large premium difference. |
| Base rate transparency (where available) helps explain regional pricing differences. | Expense load and profit margin differences between insurers aren’t always disclosed. |
| Asking for a breakdown often reveals genuinely actionable improvement opportunities. | Not all insurers are equally willing to share a detailed breakdown on request. |
⚠️ WARNING: Never assume a renewal increase reflects a single obvious cause without asking. Multiple small multiplier changes — a slightly higher base rate, a reclassified location, an aging vehicle — can compound together into a much larger total increase than any single factor would suggest.
| Your Situation | Our Recommendation |
| You want to understand exactly why your premium is what it is | Yes — ask your insurer or broker for a base rate and rating factor breakdown |
| You’re comparing quotes from multiple insurers | Yes — ask about expense load and profit margin differences, not just the final number |
| Your premium increased and you’re unsure why | Yes — request a comparison of this year’s and last year’s specific rating factors |
| You want to actively lower your calculated premium | Yes — identify which specific multipliers you can realistically improve, like claims history |
| You’re choosing between two similar vehicles for insurance purposes | Yes — ask how each vehicle’s specific multiplier compares before purchasing |
| You assume your premium is a single arbitrary number | No — ask for the formula breakdown, since it’s genuinely calculated from specific factors |
| You’re a small business comparing commercial insurance quotes | Yes — compare the full formula breakdown, not just the bottom-line premium |
💡 TIP: The single golden rule for understanding premium calculations: ask for the base rate and rating factor breakdown directly, since most insurers can explain the actual math behind your specific number if you ask.
| Scenario | Multiplier Applied | Effect on Premium |
| Base rate, standard auto policy | 1.0x (starting point) | $900/year baseline |
| Driver age 22 (higher-risk age bracket) | 1.35x | Raises premium by 35% |
| Driver age 45 (lower-risk age bracket) | 0.95x | Lowers premium by 5% |
| High-traffic urban ZIP code | 1.10x | Raises premium by 10% |
| Rural, low-traffic ZIP code | 0.90x | Lowers premium by 10% |
| One at-fault claim in past 3 years | 1.15x–1.30x | Raises premium 15%–30% |
| Clean record, continuous coverage, 10+ years | 0.85x–0.95x | Lowers premium 5%–15% |
Independent insurance brokers — Brokers can request a rating factor breakdown on your behalf and explain it in plain language. Cost range: typically free for the consumer. Best for: anyone wanting a clear explanation of their specific premium. Rating: varies by broker, check state or FCA licensing.
Your state insurance department (US) — Can confirm whether a specific rate filing or factor methodology has been formally approved. Cost range: free to contact. Best for: US consumers verifying a specific calculation. Rating: government regulatory body.
NAIC consumer resources (US) — Publishes plain-language guidance on how rating factors are typically structured across US states. Cost range: free public resource. Best for: US consumers researching premium calculation methods. Rating: regulatory standards body.
Financial Conduct Authority (UK) — Sets fairness standards for how UK insurers must structure and disclose pricing factors. Cost range: free to consult guidance. Best for: UK consumers wanting to understand pricing fairness rules. Rating: government regulatory body.
Policygenius (US) and Compare the Market (UK) — Comparison platforms that let you see how different insurers’ final calculated premiums compare for the same coverage. Cost range: free to use. Best for: shoppers wanting to compare real-world calculated outcomes. Rating: independent comparison services.
We recommend an independent broker as best overall because they can request and translate the actual rating factor breakdown behind your specific premium calculation.
Insurance companies calculate premiums by starting with a base rate for the coverage type, applying individual rating factor multipliers specific to the applicant, then adding an expense load and profit margin.
A base rate is the starting price for a specific line of insurance, calculated from aggregated historical claims data before any individual adjustments are applied.
Rating factors are specific characteristics, like age, location, or claims history, that are applied as multipliers to adjust the base rate up or down for an individual applicant.
Not usually in full detail, since exact weightings are often proprietary, but most insurers can provide a general breakdown of which factors affected your specific premium if you ask.
Multiple rating factors changing at once, such as a slightly higher base rate and a reclassified location, can compound together into a larger total increase than any single factor alone would suggest.
Yes. Vehicle type, age, and repair cost, or property construction and condition, typically have their own dedicated rating factor separate from personal factors like age or claims history.
A recent claim can raise your premium through a specific rating factor multiplier, often in the range of 15%–30%, though this varies by insurer and claim type.
No. Expense loads vary between insurers based on their specific operating costs, which can lead to different final premiums even with similar base rates and rating factors.
Yes, in many cases. Understanding which specific factors are driving your premium can help you identify realistic, actionable ways to improve your rate over time.
Even small differences in specific rating factors, like exact location or claims history details, can lead to genuinely different multipliers and therefore different final premiums.
This article is for informational purposes only. Always consult a licensed insurance professional before making coverage decisions. Trust My Policy does not sell insurance products or represent any insurer.

Jagadeesh Gutha is the founder of TrustMyPolicy.com, an independent insurance information platform covering life, health, car, home, and business insurance for US and UK readers. He researches insurance products, policy structures, and consumer rights to help everyday people make informed coverage decisions without the jargon. All content on TrustMyPolicy is independently researched, fact-checked, and written to educate — not to sell.

Insurance Guides for UK, USA & Worldwide We are not an insurer or broker.
Reader Comments (1)
[…] insurance premium is the amount you pay, usually monthly or annually, to keep a policy active. It’s calculated […]