
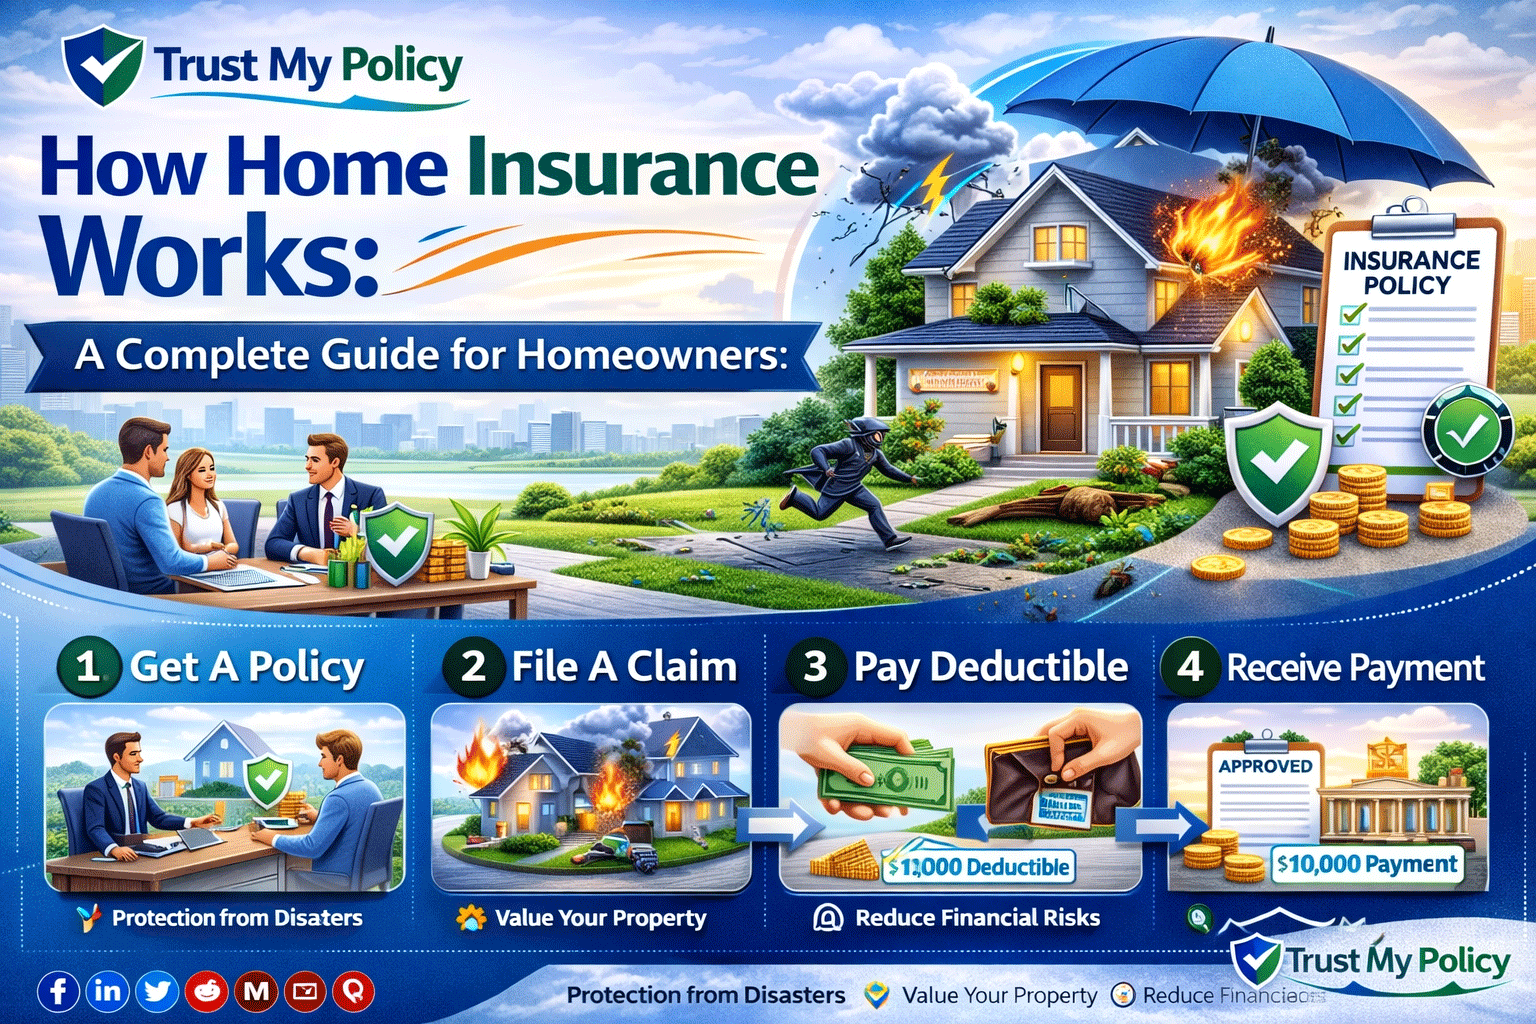
Home insurance works by pooling premiums to pay covered claims, but how much you actually receive depends on whether your policy pays replacement cost value (full cost to rebuild or replace, no depreciation) or actual cash value (replacement cost minus depreciation for age and wear). Most modern homeowners policies pay replacement cost for the dwelling structure but often pay actual cash value for personal belongings unless you’ve added a specific replacement cost endorsement for contents.
Connie Albright, 58, lost her roof and several rooms of furniture to a house fire in Cincinnati and was confused when her contents claim payout came in noticeably lower than what she’d paid for those items originally. Her policy paid actual cash value for her belongings, which meant depreciation had been subtracted from the original price, while her home’s structure was rebuilt at full replacement cost under a different part of the same policy.
How Home Insurance Works in 2026 hinges on a distinction most homeowners never think about until they file a claim: whether your payout is calculated using replacement cost value (the cost to rebuild or replace new, with no depreciation) or actual cash value (replacement cost minus depreciation). This single mechanical difference can mean a payout gap of thousands of dollars on the exact same loss. This guide breaks down exactly how insurers calculate what they actually pay you.
This article covers the replacement cost versus actual cash value distinction, how the coinsurance penalty can reduce a payout further, real scenarios with specific numbers, and what to check on your own policy. By the end, you’ll understand exactly how your payout gets calculated before you ever need to file a claim.
| Feature | Details |
| What it is | The mechanical process insurers use to calculate your actual claim payout |
| Who it affects | Every homeowner filing a claim for structure damage or personal property loss |
| Two core valuation methods | Replacement cost value (RCV) and actual cash value (ACV) |
| Typical gap between methods | 20%–50% lower payout under ACV for older items |
| Key benefit | Understanding this distinction helps you choose the right coverage before a loss occurs |
| Key limitation | Many policies default to ACV for personal belongings unless you specifically upgrade |
| Regulator | State insurance departments (US); Financial Conduct Authority (UK) |
Think of actual cash value like selling a five-year-old laptop, where the price reflects its current depreciated worth, not what you originally paid. Replacement cost value is like getting a brand-new laptop instead, with no deduction for how long you owned the old one. The exact same loss can result in a very different payout depending on which method your policy uses.
Replacement cost value pays the full cost to rebuild your home or replace your belongings with new items of similar kind and quality, without subtracting for depreciation. Actual cash value pays replacement cost minus depreciation, accounting for the age and condition of the damaged item at the time of loss. Most modern homeowners policies pay replacement cost for the dwelling structure itself, but many still default to actual cash value for personal belongings unless you’ve specifically added a replacement cost endorsement for contents.
| Criteria | Replacement Cost Value (RCV) | Actual Cash Value (ACV) |
| Calculation | Full cost to rebuild or replace with new, no depreciation | Replacement cost minus depreciation for age and condition |
| Typical use | Standard for dwelling coverage on most modern policies | Common default for personal property unless upgraded |
| Payout size | Higher, reflects true cost to replace | Lower, can be significantly less for older items |
| Pros | Provides a more complete, realistic payout for rebuilding or replacing | Lower premium cost compared to RCV coverage |
| Cons | Slightly higher premium cost | Can leave you with a meaningful out-of-pocket gap on older belongings |
We recommend confirming you have replacement cost coverage for both your dwelling and personal property for most readers, since the actual cash value gap on older belongings can be substantial.
Scenario 1: Connie, 58, homeowner in Cincinnati. Connie’s contents claim paid actual cash value, depreciating her belongings’ original price, while her home’s structure was rebuilt at full replacement cost under a different policy section. Verdict: the same policy can use different valuation methods for different coverage parts. Action: Connie added a replacement cost endorsement for personal property at her next renewal.
Scenario 2: A homeowner in Manchester whose underinsured dwelling triggered a coinsurance penalty. Insured for only 65% of his home’s actual rebuild cost, his $20,000 partial loss claim was reduced proportionally due to the coinsurance clause. Verdict: underinsuring your dwelling can reduce your payout even on a partial, not total, loss. Action: he increased his dwelling coverage limit to match a current professional rebuild-cost estimate.
Scenario 3: A family in Houston whose 10-year-old furniture was destroyed in a fire, covered under actual cash value. Their payout reflected significant depreciation, well below the cost of buying comparable new furniture. Verdict: actual cash value can create a real financial gap for replacing older belongings. Action: the family used the payout as a partial contribution and covered the remaining replacement cost themselves, then upgraded to replacement cost coverage going forward.
Scenario 4: A homeowner in Leeds with full replacement cost coverage on both dwelling and contents. A kitchen fire resulted in a payout that fully covered rebuilding and replacing damaged items with new equivalents, with no depreciation subtracted. Verdict: replacement cost coverage on both fronts avoided any unexpected payout gap. Action: the homeowner confirmed this coverage remains in place at each subsequent renewal.
| Pros | Cons |
| Replacement cost coverage provides a more complete, realistic payout. | Actual cash value can leave a significant gap for replacing older belongings. |
| Understanding this distinction helps you choose the right coverage before a loss. | Many policies still default to actual cash value for personal property. |
| Confirming your dwelling coverage matches rebuild cost avoids a coinsurance penalty. | The two-stage payout process for some RCV policies requires completing repairs first. |
| This mechanism is consistent and explainable once understood. | Many homeowners only discover their valuation method after filing a claim. |
| Upgrading to replacement cost coverage is often a modest additional premium cost. | Calculating accurate rebuild cost requires a periodic professional reassessment. |
⚠️ WARNING: Never assume your personal property is covered at replacement cost just because your dwelling is. Many policies default to actual cash value for belongings specifically, which can result in a significant, unexpected payout gap for older items.
| Your Situation | Our Recommendation |
| You haven’t confirmed your personal property valuation method | Yes — ask your insurer directly whether it’s replacement cost or actual cash value |
| Your dwelling coverage hasn’t been reassessed in several years | Yes — get a current professional rebuild-cost estimate |
| You’re insured below 80% of your home’s actual rebuild cost | Yes — increase your coverage to avoid a potential coinsurance penalty |
| You have valuable or relatively new belongings | Yes — strongly consider a replacement cost endorsement for personal property |
| You’re unsure how a two-stage replacement cost payout works | Yes — ask your insurer to explain this process before you ever need to file a claim |
| You’ve recently renovated or upgraded your home | Yes — update your dwelling coverage limit to reflect the new rebuild cost |
| You assumed your whole policy uses one consistent valuation method | No — confirm this separately for dwelling versus personal property coverage |
💡 TIP: The single golden rule for understanding home insurance payouts: confirm separately whether your dwelling and your personal property are each covered at replacement cost or actual cash value, since these can differ within the same policy.
| Scenario | Valuation Method | Payout Outcome |
| 5-year-old sofa, $1,500 original cost, destroyed in a fire | Actual cash value | Payout reduced by depreciation, often $600–$900 |
| Same sofa under a replacement cost endorsement | Replacement cost value | Full $1,500 (or current cost of similar new item) paid |
| Home insured at 65% of $400,000 rebuild cost, $20,000 partial loss | Coinsurance penalty applies | Payout reduced proportionally, potentially by several thousand dollars |
| Home insured at 100% of rebuild cost, same $20,000 partial loss | No coinsurance penalty | Full $20,000 covered, minus standard deductible |
| 10-year-old furniture set, actual cash value | Actual cash value | Payout can be 30%–50% below replacement cost |
| Dwelling structure, standard modern policy | Replacement cost value (standard for most dwellings) | Full rebuild cost paid, no depreciation applied |
| UK buildings insurance, standard policy | Typically reinstatement (replacement) cost | Generally similar to US replacement cost value structure |
Your insurer’s policy documents — The most reliable source for confirming your specific valuation method for both dwelling and personal property coverage. Cost range: free to review. Best for: confirming your exact policy terms directly. Rating: not applicable, primary source document.
Independent insurance brokers — Brokers can confirm your specific valuation methods and recommend a replacement cost endorsement if needed. Cost range: typically free for the consumer. Best for: any homeowner wanting a clear breakdown before a claim arises. Rating: varies by broker, check state or FCA licensing.
Professional appraisers or rebuild-cost estimators — Provide an accurate current estimate of your home’s actual rebuild cost, helping you avoid a coinsurance penalty. Cost range: typically $300–$600 for a professional assessment. Best for: homeowners who haven’t reassessed their dwelling coverage in several years. Rating: varies by provider, check local licensing.
NAIC consumer resources (US) — Publishes plain-language guidance on replacement cost versus actual cash value and the coinsurance clause. Cost range: free public resource. Best for: US consumers researching home insurance valuation methods. Rating: regulatory standards body.
Financial Conduct Authority (UK) — Sets standards for how UK insurers must disclose reinstatement cost and valuation terms. Cost range: free to consult guidance. Best for: UK consumers wanting to understand valuation disclosure rules. Rating: government regulatory body.
We recommend reviewing your own policy documents first as best overall, since your exact valuation method for dwelling versus personal property can vary even within the same insurer’s product lineup.
Home insurance pools premiums to pay covered claims, but your actual payout depends on whether your policy uses replacement cost value, which pays the full cost to rebuild or replace, or actual cash value, which subtracts depreciation.
Replacement cost value pays the full cost to rebuild or replace with new items, while actual cash value pays that same amount minus depreciation for the age and condition of the damaged item.
Most modern policies pay replacement cost for the dwelling structure itself, though this requires your coverage limit to accurately reflect your home’s actual rebuild cost.
This is likely because your policy pays actual cash value for personal belongings, subtracting depreciation, rather than the full replacement cost of new equivalent items.
A coinsurance penalty reduces your payout proportionally if your dwelling is insured below a required percentage, typically 80%, of its actual rebuild cost, even on a partial loss.
Yes, in most cases, by adding a replacement cost endorsement, which removes the depreciation deduction that applies under standard actual cash value coverage.
Some replacement cost policies pay actual cash value first, then release the remaining replacement cost difference once you’ve actually completed the repairs or replacement.
Get a current professional rebuild-cost estimate and ensure your dwelling coverage limit meets or exceeds the required percentage, typically 80%, of that estimate.
UK buildings insurance is typically based on reinstatement (replacement) cost, similar in principle to the US replacement cost value structure for dwelling coverage.
Reassess your home’s rebuild cost periodically, and especially after any significant renovation, to ensure your dwelling coverage limit stays accurate and avoids a coinsurance penalty.
This article is for informational purposes only. Always consult a licensed insurance professional before making coverage decisions. Trust My Policy does not sell insurance products or represent any insurer.

Jagadeesh Gutha is the founder of TrustMyPolicy.com, an independent insurance information platform covering life, health, car, home, and business insurance for US and UK readers. He researches insurance products, policy structures, and consumer rights to help everyday people make informed coverage decisions without the jargon. All content on TrustMyPolicy is independently researched, fact-checked, and written to educate — not to sell.
Insurance Guides for UK, USA & Worldwide We are not an insurer or broker.
Reader Comments (0)