
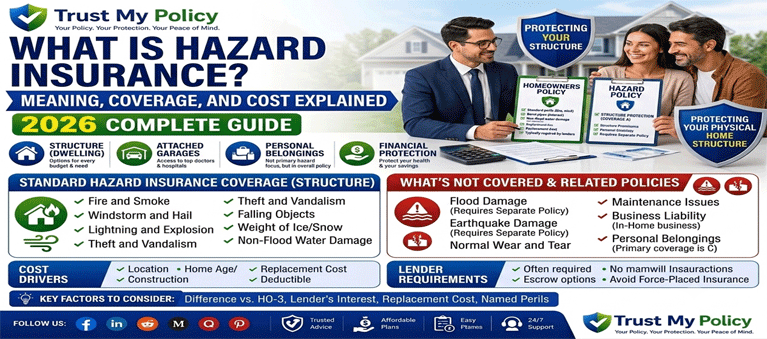
Hazard insurance isn’t actually a standalone product you can buy on its own — it’s a term, used mostly by US mortgage lenders, for the part of a homeowners insurance policy that covers damage to your home’s physical structure from specific events like fire, windstorms, hail, lightning, theft, and vandalism. In insurance terms, these covered events are called “perils,” and this piece of coverage is usually labeled dwelling coverage or Coverage A on your policy.
If you have a mortgage, your lender will almost always require you to carry it, because the home is their collateral. Standard hazard coverage does not include floods or earthquakes — those need their own separate policies.
A quick note on scope: “hazard insurance” is largely a US term rooted in mortgage lending practice. Outside the US, the same underlying protection — insuring a building’s structure against fire, storm, and similar physical damage — typically goes by other names, like buildings insurance or property (fire and perils) insurance. We’ll cover both.
Here’s the part that trips people up: hazard insurance isn’t its own product. You can’t call an insurer and buy “a hazard insurance policy” the way you’d buy a life insurance policy. It’s a piece — specifically the structural piece — of a broader homeowners insurance policy.
The name comes from how mortgage lenders talk. When your loan documents say you’re required to carry “hazard insurance,” they mean you need enough dwelling coverage in your homeowners policy to protect the physical structure that’s securing their loan. It’s really just industry shorthand.
What it typically protects:
What it’s built to respond to — a defined list of perils, commonly including fire, lightning, windstorm, hail, smoke, theft, vandalism, and falling objects.
This is the single most common point of confusion, so it’s worth being precise about it.
| Hazard Insurance | Homeowners Insurance | |
| What it is | One coverage section within a homeowners policy | The full policy package |
| What it protects | The home’s physical structure only | Structure, personal belongings, liability, additional living expenses, and more |
| Can you buy it separately? | No — it’s not a standalone product | Yes, it’s the actual policy you purchase |
| Who uses the term | Mostly mortgage lenders and loan documents | Insurers, everyone else |
Put simply: every homeowners policy includes hazard (dwelling) coverage, but a homeowners policy is much bigger than that one piece. If your home burns down, hazard/dwelling coverage pays to rebuild it. If a guest is injured on your property, that’s a completely different part of the policy — liability coverage, not hazard coverage.
Typically covered perils:
Typically excluded — and requiring separate coverage:
Exactly which perils are covered — and which are excluded — varies by insurer, by policy form, and by location, so the specific declarations page of your policy is the only fully reliable source for what you’re covered for.
Your home is the collateral behind your mortgage. If it burns down and you have no insurance, the lender’s collateral is gone along with a chunk of your ability to keep paying the loan. That’s why virtually every mortgage contract requires the borrower to maintain hazard insurance for at least the outstanding loan balance, often for the full replacement cost of the home.
Many lenders collect hazard insurance premiums as part of your monthly mortgage payment, holding the funds in an escrow account and paying the insurer directly when the premium is due. This isn’t universal — some borrowers pay their insurer directly — but it’s common, particularly in the early years of a mortgage.
There’s no flat number that applies to everyone, because pricing is individual. Contributing factors typically include:
Because these vary so much by property and location, the only reliable way to know your actual cost is to get quotes for your specific home.
If you stop paying for hazard insurance, or your policy lapses, and your mortgage servicer can’t confirm you have adequate coverage, the servicer can buy a policy on your behalf and bill you for it. In the US, this is called force-placed insurance (also known as lender-placed insurance), and it’s regulated under the Real Estate Settlement Procedures Act (RESPA).
A few things worth knowing:
The simplest way to avoid this entirely: keep your escrow account funded, or if you pay your insurer directly, make sure your lender always has current proof of coverage on file.
“Hazard insurance” as a phrase is largely an American convention, tied to how US mortgage documents are written. If you’re outside the US, you’re unlikely to see that exact term on your paperwork — but the underlying concept, insuring a building’s structure against fire and similar physical perils, exists everywhere property is insured. It just goes by different names:
If you’re reading this from outside the US and see “hazard insurance” in a document — for example, from a US-based lender, employer, or property — it’s safe to read it as referring to the structural fire-and-perils coverage on that property.
Pros
Cons
Since hazard insurance is filed as part of your broader homeowners claim, the process looks like this:
Common reasons a claim is reduced or denied:
A homeowner in a US coastal state discovers after a hurricane that their standard hazard coverage excluded wind damage above a certain threshold, requiring a separate windstorm policy they didn’t know they needed — a gap worth checking before, not after, storm season.
A first-time buyer reviewing closing documents sees “hazard insurance” listed as a requirement and assumes they need to shop for a new, separate policy — when in reality, the homeowners insurance policy they already selected satisfies the requirement, as long as the dwelling coverage amount is sufficient.
A UK-based reader relocating for work encounters “hazard insurance” in a US mortgage document and, recognizing it as roughly equivalent to buildings insurance back home, understands it refers to structural coverage rather than a new, unfamiliar product.
(These are illustrative scenarios, not personalized recommendations.)
Is hazard insurance the same as homeowners insurance?
Not quite. Hazard insurance refers specifically to the structural (dwelling) portion of a homeowners policy. Homeowners insurance is the full package — structure, belongings, liability, and more.
Can I buy hazard insurance as a standalone policy?
No. It’s not sold separately; it comes as part of a homeowners insurance policy.
Does hazard insurance cover flooding?
No. Flood damage is excluded from standard hazard/homeowners coverage and requires a separate flood insurance policy.
Do I still need hazard insurance once my mortgage is paid off?
It’s no longer required by a lender, but most homeowners keep equivalent coverage anyway, since the home is still their asset to protect.
What is force-placed insurance?
It’s a policy a mortgage servicer buys on your behalf if your hazard insurance lapses and they can’t confirm you have adequate coverage. It’s typically far more expensive and covers less than a policy you’d choose yourself.
Is “hazard insurance” used outside the United States?
Rarely as an exact term. Other countries use names like buildings insurance (UK) or property/fire insurance, but the underlying concept — insuring a structure against fire and similar perils — is essentially universal.
How much hazard insurance coverage do I need?
Enough to cover your home’s full replacement cost — what it would actually cost to rebuild — not necessarily its market value. A local insurance agent can help calculate this accurately for your specific property.
Mandatory Legal Disclaimer: This article is for informational and educational purposes only. Always consult a licensed insurance broker or qualified financial advisor before purchasing coverage. Trust My Policy does not sell insurance products or represent any insurer.

Jagadeesh Gutha is the founder of TrustMyPolicy.com, an independent insurance information platform covering life, health, car, home, and business insurance for US and UK readers. He researches insurance products, policy structures, and consumer rights to help everyday people make informed coverage decisions without the jargon. All content on TrustMyPolicy is independently researched, fact-checked, and written to educate — not to sell.

Insurance Guides for UK, USA & Worldwide We are not an insurer or broker.
Reader Comments (0)