
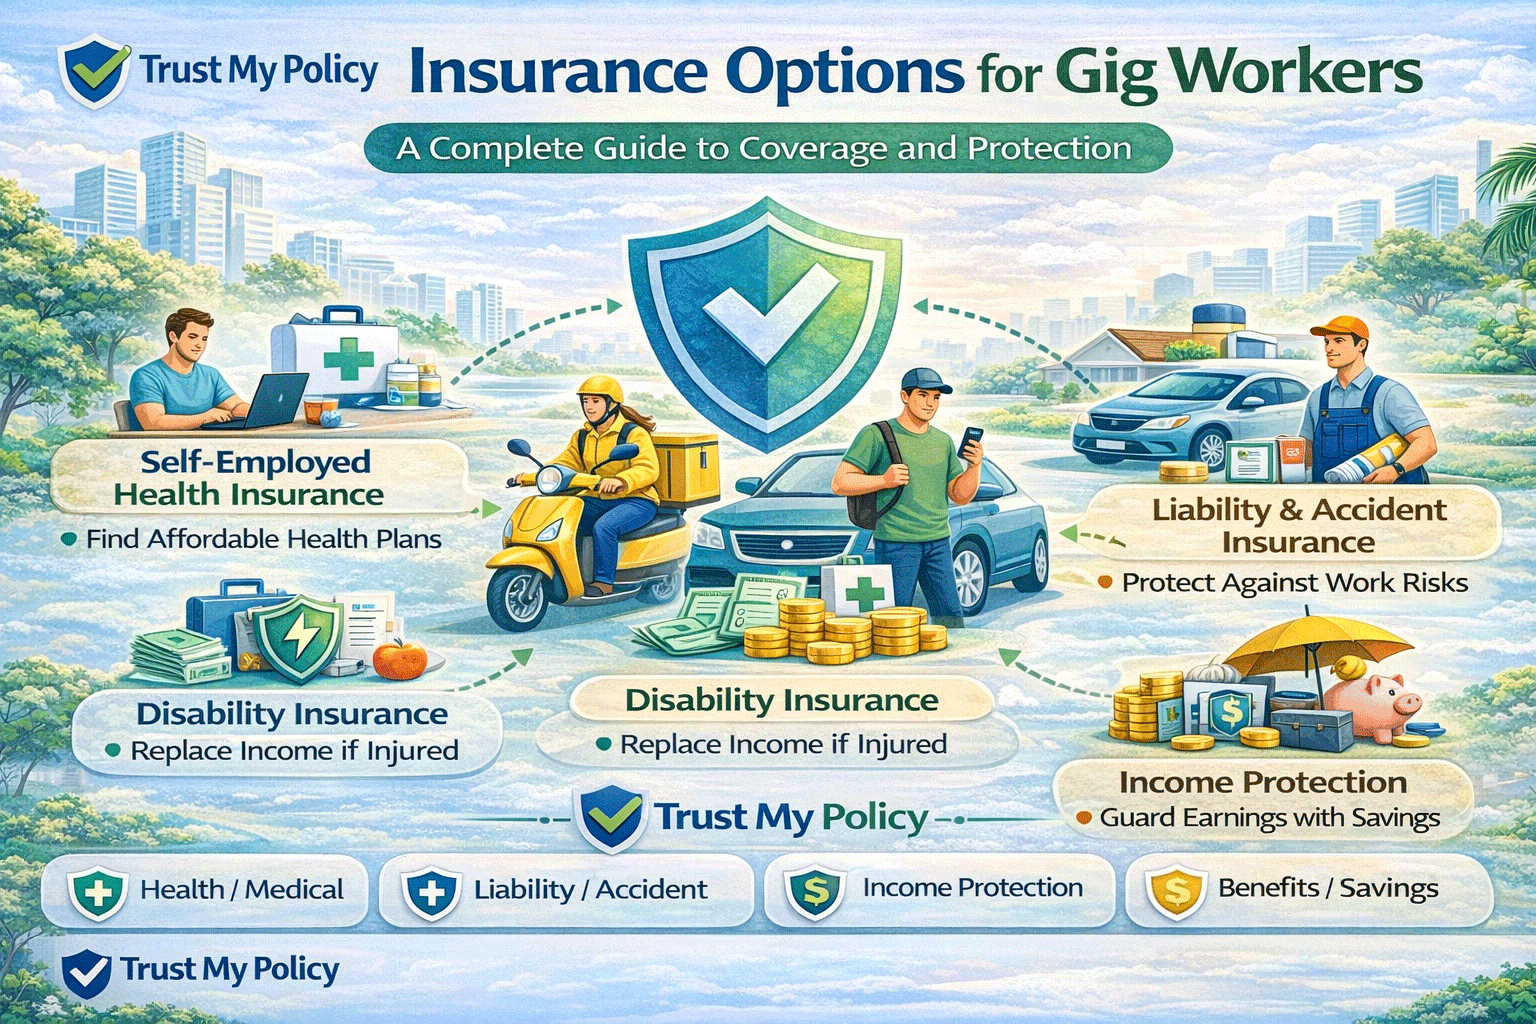
Gig workers need a rideshare or delivery endorsement to close the gap during the period when the app is on but no ride or delivery has been accepted, since platform coverage during this window is typically limited to $50,000 per person and $25,000–$30,000 in property damage, with no coverage for your own vehicle. Gig workers also need individual health insurance and should consider occupational accident or disability coverage, since platforms classify drivers as independent contractors with no employer benefits.
Maria Stenholm, 42, drove for a rideshare app in Atlanta and was waiting at a shopping center for her next ride request when another driver hit her. Her personal auto insurer denied the claim, citing commercial use, and the rideshare platform’s coverage during that specific waiting period turned out to be far thinner than she’d assumed.
Insurance Options for Gig Workers in 2026 need to address three distinct gaps most platforms don’t fully close: auto coverage during the specific “waiting for a request” period, health insurance since gig platforms don’t provide it, and income protection if an injury keeps you from working. This guide breaks down exactly which gaps exist for rideshare, delivery, and other gig platforms, and the specific products designed to close them.
This article covers the real coverage gaps in platform-provided insurance, the specific products built to close them, real scenarios with dollar figures, and a clear framework for building your own coverage stack. By the end, you’ll know exactly where your platform’s coverage ends and yours needs to begin.
| Feature | Details |
| What it is | A combination of auto, health, and income protection coverage built around gig platform gaps |
| Who needs it | Rideshare drivers, delivery drivers, and other app-based independent contractors |
| Biggest auto coverage gap | The period when the app is on but no ride/delivery has been accepted |
| Typical added cost | $10–$30/month for a rideshare/delivery endorsement |
| Key benefit | Closes specific, well-documented gaps platforms don’t fully cover |
| Key limitation | Gig workers must assemble this coverage themselves; it’s rarely provided automatically |
| Regulator | State insurance departments (US); Financial Conduct Authority (UK) |
Picture your coverage like three relay runners passing a baton. Your personal auto policy carries the baton until you turn the app on. The platform’s policy is supposed to pick it up from there, but it only runs at full strength once you’ve actually accepted a ride or delivery. In between, during that waiting period, the baton can drop entirely unless you’ve specifically planned for it.
Gig worker insurance gaps fall into three categories: the auto coverage gap during the period your app is on but no job is accepted, the complete absence of employer-provided health insurance, and the lack of any income protection if an injury prevents you from working. Most rideshare and delivery platforms provide some contingent coverage, but it’s deliberately structured in phases, and the weakest phase is exactly the one many drivers spend the most time in.
| Criteria | Platform-Provided Coverage | Personal Add-On Coverage (Endorsement, Health, Income Protection) |
| Coverage during waiting period | Limited liability only, no vehicle damage coverage | A rideshare/delivery endorsement extends meaningful coverage during this exact gap |
| Health insurance | None provided by gig platforms | Must be arranged individually through a marketplace or private plan |
| Income protection if injured | None provided by gig platforms | Optional occupational accident or disability insurance can be added |
| Pros | Free, automatically included while using the app | Specifically closes the gaps platforms leave open |
| Cons | Thin coverage during the highest-risk waiting period | Requires proactive setup and an additional monthly cost |
We recommend every gig worker add a rideshare or delivery endorsement and secure individual health insurance for most readers, since both address well-documented, common gaps rather than rare edge cases.
Scenario 1: Maria, 42, rideshare driver in Atlanta. Maria’s accident during the app-on waiting period left her with limited liability coverage and no protection for her own vehicle’s damage. Verdict: this exact waiting period is the most commonly cited coverage gap for rideshare drivers. Action: Maria added a rideshare endorsement covering both the waiting period and her own vehicle damage going forward.
Scenario 2: Devon, 27, delivery driver in Manchester using his own car. Devon discovered his delivery platform provided only third-party liability during an active delivery, with no coverage at all for his own vehicle damage. Verdict: delivery platform coverage is often thinner than rideshare coverage, even during active deliveries. Action: Devon added a delivery-specific endorsement that included contingent collision coverage for his own car.
Scenario 3: Priya, 33, full-time gig worker combining rideshare and food delivery in Houston. With no employer health plan, Priya went a year without coverage before a $6,400 emergency room bill changed her mind. Verdict: gig platforms provide zero health insurance, regardless of how many hours you work. Action: Priya enrolled in a marketplace health plan and budgets the premium as a fixed monthly business cost.
Scenario 4: A rideshare driver in Phoenix who broke his wrist in a non-driving accident. With no employer disability coverage and no savings cushion, he lost three weeks of income with no way to replace it. Verdict: gig workers carry full income risk with no automatic safety net if they’re unable to work. Action: he later added an individual occupational accident policy specifically to cover gaps like this.
| Pros | Cons |
| Platform coverage during active rides or deliveries is often substantial. | The waiting-period gap is a well-documented, common source of disputed claims. |
| Rideshare and delivery endorsements are relatively affordable to add. | Gig workers must proactively arrange this coverage themselves. |
| Marketplace health insurance is available regardless of platform work. | No platform provides health insurance, regardless of hours worked. |
| Occupational accident insurance can replace lost income after an injury. | Most gig workers go without any income protection by default. |
| Disclosing gig work to your personal insurer prevents a denied claim later. | Personal insurers can cancel a policy entirely if undisclosed commercial use is discovered. |
⚠️ WARNING: Never assume your personal auto policy or your platform’s coverage alone fully protects you during the entire time your app is turned on. The waiting period between turning on the app and accepting a ride or delivery is the single most commonly cited coverage gap for gig drivers.
| Your Situation | Our Recommendation |
| You drive for any rideshare or delivery platform | Yes — add a rideshare or delivery endorsement to your personal auto policy |
| You haven’t disclosed your gig work to your personal insurer | Yes — disclose it immediately to avoid a denied claim and policy cancellation |
| You don’t have health insurance through any other source | Yes — enroll in a marketplace or private health insurance plan |
| You have no savings cushion if an injury stops you from working | Yes — consider occupational accident or disability insurance |
| You only occasionally use a gig platform for extra income | Yes — still disclose the activity, even if usage is infrequent |
| You’re unsure what your platform’s physical damage deductible is | Yes — check this specific figure before assuming a claim will be fully covered |
| You combine multiple gig platforms (rideshare and delivery) | Yes — confirm your endorsement covers all the specific platforms you use |
💡 TIP: The single golden rule for gig worker insurance: the gap between turning your app on and accepting a job is where coverage is thinnest, so build your own protection specifically around that window.
| Scenario | Cost | Notes |
| Rideshare endorsement on personal auto policy | $10–$25/month | Closes the waiting-period gap and adds contingent vehicle coverage |
| Delivery endorsement on personal auto policy | $8–$20/month | Often necessary since delivery platform coverage is typically thinner |
| Marketplace health insurance, subsidized | $0–$240/month | Varies significantly by income and household size |
| Marketplace health insurance, unsubsidized | $400–$700/month | Standard Bronze to Silver tier range |
| Occupational accident insurance for gig workers | $20–$60/month | Provides income replacement and medical coverage after a work-related injury |
| Platform contingent collision/comprehensive deductible | ~$2,500 | Applies during active ride or delivery phases for most rideshare platforms |
| Personal policy deductible (if disclosed and endorsed) | $500–$1,000 | Often lower than the platform’s own deductible during active phases |
Mercury Insurance and other rideshare-specific auto insurers (US) — Offer dedicated rideshare endorsements designed specifically to close the waiting-period gap. Cost range: competitive add-on pricing. Best for: US rideshare drivers wanting a purpose-built endorsement. Rating: AM Best A.
Progressive and GEICO (US) — Both offer rideshare endorsements as an add-on to standard personal auto policies. Cost range: competitive US pricing. Best for: drivers wanting to add coverage to an existing policy. Rating: AM Best A+ and A++ respectively.
Admiral and Aviva (UK) — Offer specific guidance and add-on policies for UK private hire and delivery drivers. Cost range: competitive UK pricing. Best for: UK gig drivers needing commercial-use add-ons. Rating: Defaqto 4-5 Star.
HealthCare.gov (US) — The federal marketplace for individual health insurance, essential for any gig worker without other coverage. Cost range: free to compare, premiums vary by plan. Best for: US gig workers without employer health coverage. Rating: federal government marketplace.
Occupational accident insurance providers (specialty US carriers) — Offer income replacement and injury coverage specifically designed for independent contractors. Cost range: competitive specialty pricing. Best for: gig workers wanting income protection without employer disability coverage. Rating: varies by provider, check AM Best ratings.
We recommend starting with a rideshare or delivery endorsement as best overall first step because it directly closes the most commonly documented and highest-risk gap gig workers face.
Gig workers typically need a rideshare or delivery endorsement on their personal auto policy, individual health insurance since platforms don’t provide it, and optionally, income protection through occupational accident insurance.
Not fully. The period when the app is on but no ride has been accepted carries much thinner coverage than the period after you accept a ride, leaving a real gap many drivers don’t realize exists.
Yes. Failing to disclose gig driving can result in a denied claim and a canceled policy if your insurer discovers undisclosed commercial use after an accident.
During this specific waiting period, most platforms provide no coverage for your own vehicle damage, which is why a rideshare endorsement is specifically designed to close this gap.
No. Gig platforms classify workers as independent contractors, meaning no employer-provided health insurance, regardless of how many hours you work on the platform.
Yes, for many gig workers, since it provides income replacement and medical coverage after a work-related injury, addressing a gap that otherwise leaves you with zero income protection.
It’s typically around $2,500 for major rideshare platforms during active ride phases, which is often significantly higher than a personal policy’s standard deductible.
No, in most cases. Personal auto policies typically exclude commercial use, which includes rideshare and delivery driving, making a specific endorsement necessary.
Often yes. Delivery platform coverage can be thinner than rideshare coverage, sometimes providing only third-party liability during an active delivery with no vehicle damage coverage at all.
Most rideshare or delivery endorsements cost between $8 and $25 a month, which is a relatively small cost relative to the specific, well-documented gap it closes.
This article is for informational purposes only. Always consult a licensed insurance professional before making coverage decisions. Trust My Policy does not sell insurance products or represent any insurer.

Jagadeesh Gutha is the founder of TrustMyPolicy.com, an independent insurance information platform covering life, health, car, home, and business insurance for US and UK readers. He researches insurance products, policy structures, and consumer rights to help everyday people make informed coverage decisions without the jargon. All content on TrustMyPolicy is independently researched, fact-checked, and written to educate — not to sell.
Insurance Guides for UK, USA & Worldwide We are not an insurer or broker.
Reader Comments (0)