
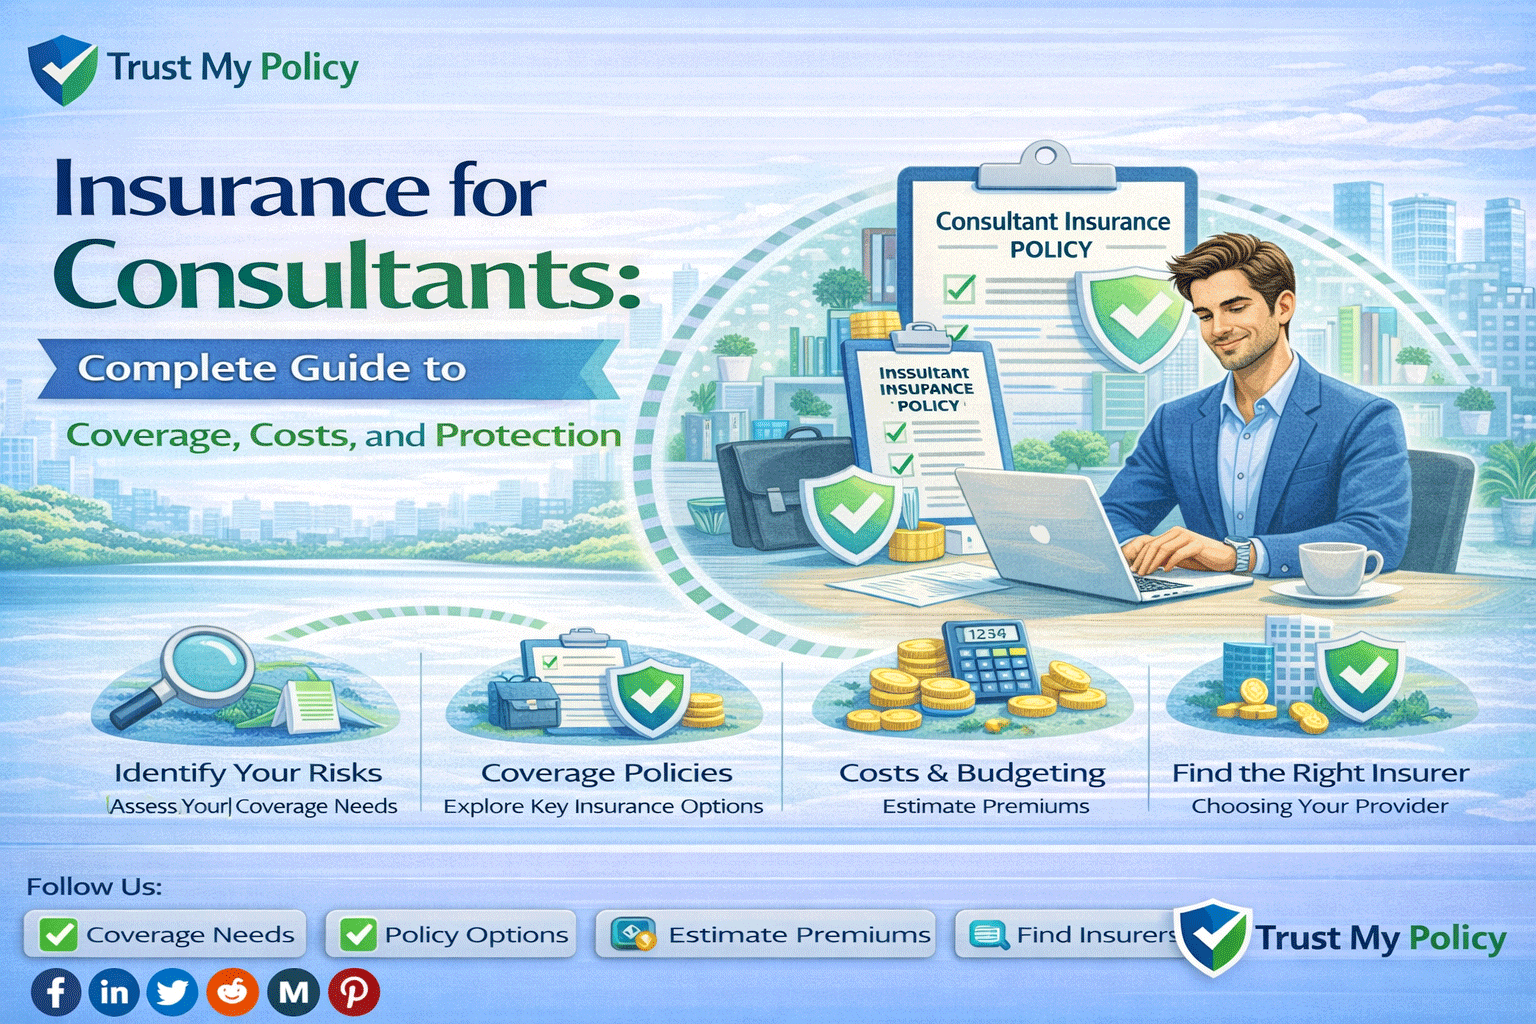
Consultants typically need professional liability (errors and omissions) insurance to cover claims about the quality or accuracy of their advice, general liability insurance for any in-person client interactions, and cyber liability if they handle client data. Many corporate clients now require proof of $1 million to $2 million in professional liability coverage as a contract precondition, so consultants should secure coverage before, not after, a major client requires it.
Adrian Fenwick, 38, ran a management consulting practice in Chicago for three years without any business insurance, until a Fortune 500 client’s procurement department sent over a vendor agreement requiring $2 million in professional liability coverage as a precondition of signing. He had 72 hours to bind a policy or lose the contract entirely.
Insurance for Consultants in 2026 centers on three coverage types most independent and small-firm consultants need: professional liability (errors and omissions) insurance to cover claims about your advice, general liability insurance for any in-person client meetings or events, and cyber liability if you handle any client data electronically. Increasingly, large corporate clients require specific minimum coverage amounts before they’ll sign a contract at all. This guide breaks down exactly what to buy, how much, and how to respond when a client contract demands it.
This article covers the core coverage consultants need, how client contract requirements typically work, real scenarios with specific numbers, and a clear framework for getting coverage in place before you need it. By the end, you’ll know exactly what to have ready before your next client agreement lands in your inbox.
| Feature | Details |
| What it is | A combination of professional liability, general liability, and sometimes cyber coverage tailored to consulting work |
| Who needs it | Independent consultants, small consulting firms, and advisory practices |
| Typical cost | $500–$3,000/year depending on coverage limits and consulting specialty |
| Common client requirement | $1,000,000–$2,000,000 in professional liability coverage as a contract precondition |
| Key benefit | Protects against claims related to your advice and satisfies client contract requirements |
| Key limitation | Securing coverage under time pressure from a client deadline can limit your insurer options |
| Regulator | State insurance departments (US); Financial Conduct Authority (UK) |
Think of consulting insurance like a three-layer security badge system at a corporate building. The first layer (professional liability) covers what happens if your specific advice or analysis turns out wrong. The second layer (general liability) covers what happens if you’re physically present at a client site and something goes wrong there. The third layer (cyber liability) covers what happens if client data you’re handling gets exposed.
Consultants primarily need professional liability insurance, also called errors and omissions coverage, which protects against claims that your advice, analysis, or recommendations caused a client financial harm. General liability insurance covers physical injury or property damage during in-person client meetings, site visits, or hosted events. Cyber liability insurance becomes relevant the moment you handle any client data electronically, which describes nearly every modern consulting practice. Anyone consulting independently or through a small firm needs to evaluate all three, not just the most obvious one.
| Criteria | Independent Consultant | Small Consulting Firm (2+ Consultants) |
| Core coverage | Professional liability, general liability | Professional liability, general liability, plus workers’ compensation for any employees |
| Typical coverage limit | $1,000,000 professional liability | $1,000,000–$2,000,000 professional liability, often higher for larger client contracts |
| Cost | $500–$1,500/year | $1,500–$4,000/year, scaling with headcount and revenue |
| Pros | Simpler to set up and maintain | Can negotiate higher limits more easily with larger combined revenue |
| Cons | Lower limits may not satisfy larger corporate client requirements | More complex coverage needs as headcount grows |
We recommend independent consultants secure at least $1,000,000 in professional liability coverage proactively for most readers, since this is the most common minimum requirement in corporate client contracts.
Scenario 1: Adrian, 38, management consultant in Chicago. Adrian’s lack of existing coverage nearly cost him a major client contract when their procurement department required $2 million in professional liability insurance with only 72 hours’ notice. Verdict: large corporate clients increasingly treat specific coverage requirements as non-negotiable. Action: Adrian now maintains $2 million in professional liability coverage proactively, regardless of his current client roster.
Scenario 2: A marketing strategy consultant in Leeds working entirely remotely. She initially skipped general liability insurance, assuming her fully remote work eliminated that risk, until an in-person workshop she hosted required proof of coverage from the venue. Verdict: even primarily remote consultants can encounter situations requiring general liability coverage. Action: she added a modest general liability policy specifically to cover occasional in-person engagements.
Scenario 3: An IT strategy consultant in Austin handling sensitive client data during a digital transformation project. A data handling incident during the engagement was covered under her cyber liability policy, separate from her professional liability coverage. Verdict: data-handling consulting work carries a distinct cyber risk beyond standard professional liability. Action: she increased her cyber liability limit given the increasing sensitivity of her typical client data.
Scenario 4: A two-person HR consulting firm in Houston that grew to five consultants within a year. Their original $1,000,000 professional liability limit no longer satisfied the requirements of larger clients they began pursuing. Verdict: coverage needs to scale with both headcount and the size of client contracts being pursued. Action: the firm increased its limit to $2,000,000 and added workers’ compensation for its growing team.
| Pros | Cons |
| Satisfies increasingly common corporate client contract requirements. | Securing coverage under client deadline pressure can limit your insurer options. |
| Professional liability directly addresses the core risk of giving paid advice. | Coverage needs to scale as your client base and contract sizes grow. |
| Relatively affordable for independent consultants relative to the protection provided. | Many consultants discover a requirement only after a client contract demands it. |
| Cyber liability addresses a genuinely growing risk as more consulting work involves data. | Comparing coverage limits and specific exclusions takes real research effort. |
| Securing coverage proactively avoids scrambling under a tight contract deadline. | Premiums increase with higher coverage limits, which larger clients often require. |
⚠️ WARNING: Never sign a client contract with a specific insurance requirement without confirming your actual policy satisfies the exact coverage type and amount specified. A mismatch discovered later, during an actual claim, can leave you in breach of contract on top of the underlying dispute.
| Your Situation | Our Recommendation |
| You’re an independent consultant without any current coverage | Yes — secure at least $1,000,000 in professional liability insurance now |
| You’re pursuing larger corporate clients | Yes — proactively secure $2,000,000 in coverage before contract negotiations begin |
| You occasionally host in-person workshops or site visits | Yes — add general liability insurance, even if most of your work is remote |
| You handle any client data electronically | Yes — add cyber liability insurance to your coverage stack |
| Your consulting firm has grown beyond a single consultant | Yes — add workers’ compensation and reassess your overall coverage limits |
| You received a contract with a specific coverage requirement | Yes — confirm your policy matches the exact type and amount specified before signing |
| You haven’t reviewed your coverage limits in over a year | Yes — reassess them, especially if your typical client contract size has grown |
💡 TIP: The single golden rule for consultant insurance: secure professional liability coverage before you need it for a specific client contract, not after a procurement department gives you a 72-hour deadline.
| Scenario | Typical Annual Cost | Notes |
| Independent consultant, $1,000,000 professional liability | $500–$1,200/year | Common minimum requirement for many client contracts |
| Independent consultant, $2,000,000 professional liability | $1,000–$2,500/year | Often required for larger corporate client engagements |
| General liability add-on for occasional in-person events | $300–$600/year | Relevant even for primarily remote consultants |
| Cyber liability for data-handling consulting work | $500–$1,500/year | Scales with the sensitivity and volume of client data handled |
| Small consulting firm (3-5 consultants), combined coverage | $3,000–$7,000/year | Includes professional liability, general liability, and workers’ compensation |
| UK professional indemnity insurance, independent consultant | £300–£800/year | UK equivalent of US professional liability coverage |
| UK public liability insurance add-on | £100–£300/year | UK equivalent of US general liability for in-person engagements |
Hiscox (US and UK) — Specializes in professional liability and small business coverage well suited to independent consultants in both countries. Cost range: competitive professional liability pricing. Best for: independent consultants and small consulting firms. Rating: AM Best A.
The Hartford (US) — Offers professional liability coverage with clear guidance on meeting client contract requirements. Cost range: competitive small business pricing. Best for: US consultants needing to satisfy specific client coverage requirements. Rating: AM Best A.
Markel (US and UK) — Provides specialized professional liability coverage for niche consulting fields, including technical and regulatory consulting. Cost range: competitive specialty pricing. Best for: consultants in specialized or higher-risk fields. Rating: AM Best A.
Simply Business (UK) — A UK comparison platform specializing in professional indemnity insurance for consultants across many fields. Cost range: free to compare. Best for: UK consultants comparing indemnity coverage options. Rating: FCA-regulated comparison service.
Independent insurance brokers — Brokers can confirm whether your specific policy satisfies a client’s exact contractual coverage requirement. Cost range: typically free for the consumer. Best for: any consultant facing a specific client coverage requirement. Rating: varies by broker, check state or FCA licensing.
We recommend Hiscox as best overall because it specializes specifically in the professional liability coverage most consultants need, with straightforward documentation that satisfies common corporate client requirements.
Consultants typically need professional liability (errors and omissions) insurance for their core advisory risk, general liability insurance for any in-person client interactions, and cyber liability insurance if they handle client data.
Many corporate clients require $1,000,000 to $2,000,000 in professional liability coverage as a contract precondition, so securing at least this amount proactively is a common starting point.
Many corporate procurement departments now require vendors to carry specific minimum insurance coverage to protect against claims arising from the engagement, regardless of the consultant’s size or experience.
Often yes, in a modest amount, since even primarily remote consultants may occasionally host in-person workshops, meetings, or site visits that carry physical injury risk.
Cyber liability insurance covers costs related to a data breach or cyberattack affecting client data you handle, separate from the coverage provided by professional liability insurance.
Independent consultants typically pay $500–$2,500 a year for professional liability coverage, with additional costs for general liability or cyber liability if needed.
This can put you in breach of contract, separate from any underlying dispute, so it’s important to confirm your policy matches the specific type and amount required before signing.
Yes, generally. Coverage limits that were sufficient for smaller engagements may not satisfy the requirements or realistic risk of larger corporate client contracts.
Yes, typically workers’ compensation insurance becomes necessary once a consulting firm has employees, in addition to its professional and general liability coverage.
Many insurers can issue a policy within days for straightforward consulting risk profiles, though securing coverage proactively avoids the pressure of a tight contract deadline.
This article is for informational purposes only. Always consult a licensed insurance professional before making coverage decisions. Trust My Policy does not sell insurance products or represent any insurer.

Jagadeesh Gutha is the founder of TrustMyPolicy.com, an independent insurance information platform covering life, health, car, home, and business insurance for US and UK readers. He researches insurance products, policy structures, and consumer rights to help everyday people make informed coverage decisions without the jargon. All content on TrustMyPolicy is independently researched, fact-checked, and written to educate — not to sell.

Insurance Guides for UK, USA & Worldwide We are not an insurer or broker.
Reader Comments (0)