
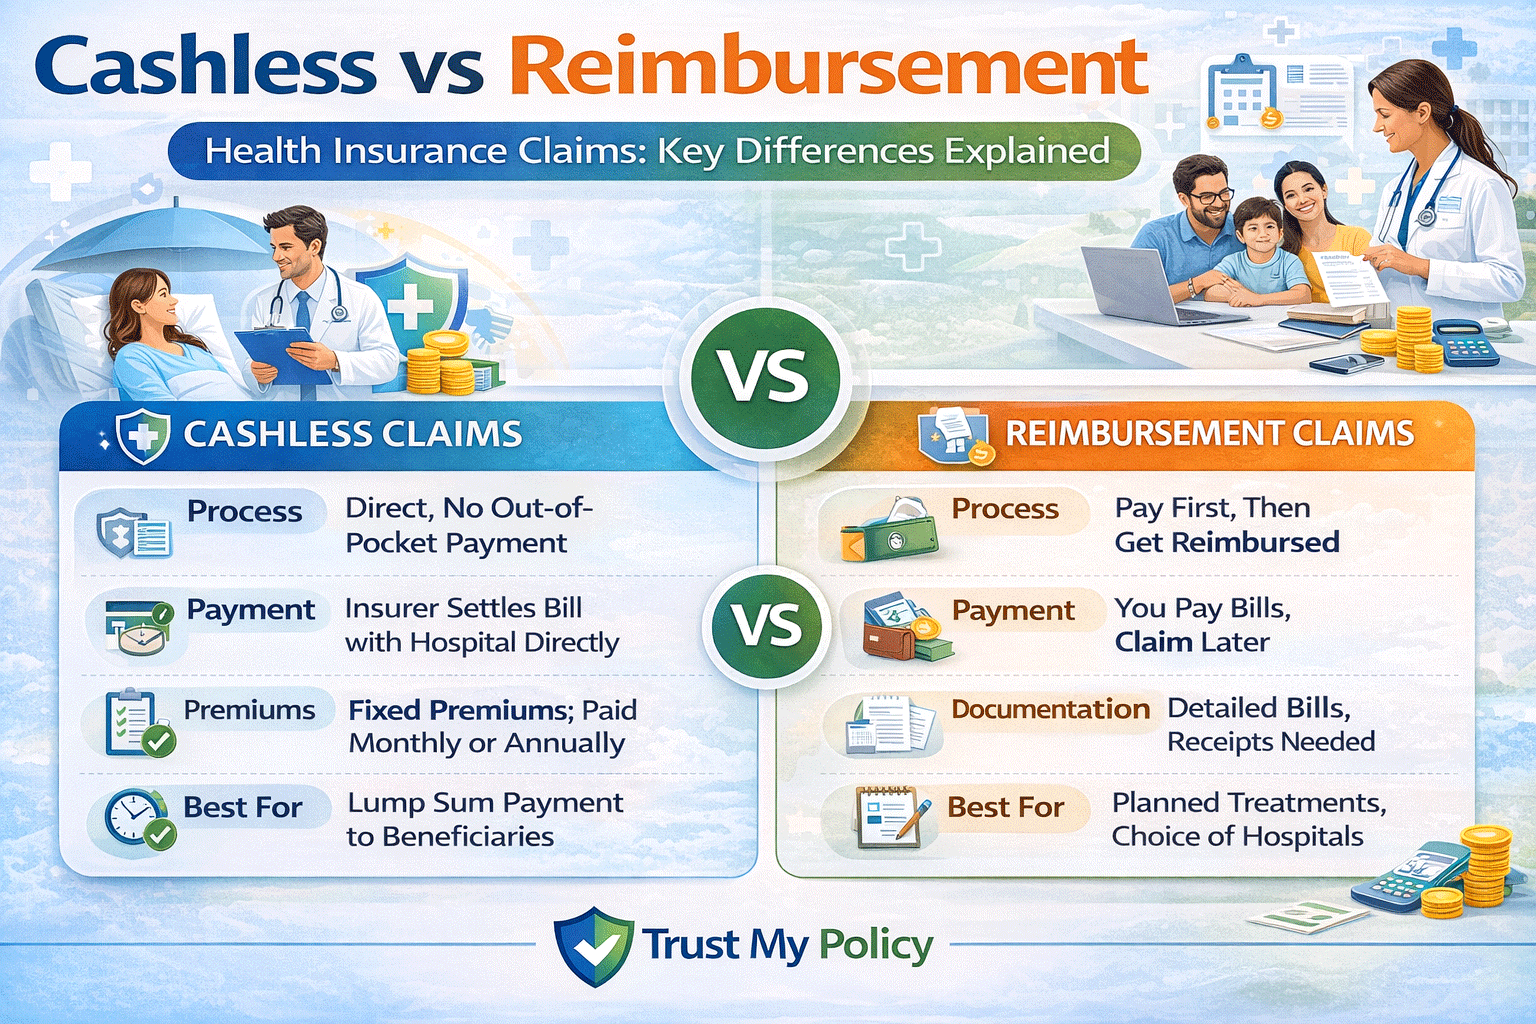
A cashless health insurance claim means your insurer pays the hospital directly — you pay nothing upfront except non-covered items and copays. It is only available at network hospitals listed by your insurer or TPA. A reimbursement claim requires you to pay the full hospital bill first, then submit documents to your insurer for repayment within 15-30 working days. Cashless is faster and more convenient for planned treatment. Reimbursement offers more hospital choice but requires upfront funds and disciplined document management.
Meena, a 37-year-old school principal from Hyderabad, had planned appendix surgery in January 2026. She booked a well-known private hospital, confident her Star Health insurance would handle everything. At discharge, the billing desk handed her a bill for Rs 1,40,000 — the hospital was not on the cashless network. She had the funds, but the shock of a six-figure out-of-pocket payment after two years of faithfully paid premiums left her furious. One phone call to her TPA before booking would have revealed four cashless network hospitals within 5 km.
Cashless vs reimbursement health insurance claims in 2026 represents the two fundamental ways your insurer settles medical bills — and choosing the wrong approach for your situation can mean paying Rs 1,00,000 or more out of pocket unnecessarily. In a cashless claim, the insurer pays the hospital directly and you pay only non-covered items at discharge. In a reimbursement claim, you pay the full bill upfront and the insurer repays you within 15-30 working days after document verification. According to IRDAI data for FY 2024-25, Niva Bupa holds a 93.7% claim settlement ratio and Star Health 91.4% — meaning well over nine in ten valid claims are paid.
In this guide you will learn exactly how both claim types work step by step, the complete document checklist for each, processing timelines, the most common reasons claims are delayed or rejected, four real-life scenarios showing which claim type to use, and the five most expensive mistakes policyholders make when filing health insurance claims.
| Feature | Cashless Claim | Reimbursement Claim |
| How it works | Insurer pays hospital directly via TPA | You pay first; insurer repays you later |
| Hospital choice | Network / empanelled hospitals only | Any hospital — network or non-network |
| Upfront payment required | No — only copay or non-covered items | Yes — full bill paid at discharge |
| Pre-authorisation needed | Yes — insurer must approve before/at admission | No — but inform insurer within 24 hrs of admission |
| Processing timeline | 2-6 hours pre-auth; settled at discharge | 15-30 working days after full document submission |
| Document burden | Low — hospital insurance desk handles most paperwork | High — you collect and submit every document |
| Best for | Planned surgery, network hospitals, limited liquid savings | Emergency at non-network, specialist preference, rural areas |
| Regulated by | IRDAI (India); FCA (UK); state DOI (US) | IRDAI (India); FCA (UK); state DOI (US) |
A cashless health insurance claim is exactly what the name says — you receive hospital treatment without paying the main bill at discharge. Your insurer pays the hospital directly through a Third Party Administrator (TPA) or a direct settlement mechanism. You present your health insurance card at admission, the hospital verifies coverage, the insurer pre-authorises the treatment, and all billing flows from hospital to insurer without touching your bank account.
Think of it like a corporate credit card. The hotel bills the company directly; you check out without paying. Cashless health insurance works the same way — the hospital is the hotel, your insurer is the company settling the account.
The critical restriction: cashless claims are only available at hospitals on your insurer’s empanelled network. Most major Indian insurers — Star Health, Niva Bupa, HDFC Ergo — have 10,000 to 25,000+ network hospitals across the country. In the UK, Bupa and AXA Health operate direct billing arrangements with hundreds of private hospitals. In the US, in-network providers work similarly — the insurer settles directly with the provider, no upfront payment required.
A reimbursement health insurance claim requires you to pay the entire hospital bill yourself at discharge, then claim the money back from your insurer by submitting a full document pack. The insurer reviews your claim, verifies coverage, and transfers the eligible amount to your bank account within 15-30 working days of receiving a complete submission.
Reimbursement is your only option when you are admitted to a non-network hospital — by choice (you want a specific specialist) or by circumstance (an emergency in an area with no network hospital nearby). It gives you complete freedom of hospital choice but demands two things: liquid funds to cover the bill at discharge, and careful document collection from day one of admission.
The most common reason reimbursement claims are delayed or rejected is missing documents. A single absent receipt, investigation report, or discharge summary can delay payment by weeks or trigger a partial settlement. Discipline at the hospital — collecting every piece of paper as it is issued — is the single most important factor in a smooth reimbursement.
If a reimbursement claim is rejected or underpaid, follow the appeal steps in our guide on why insurance claims get rejected and how to appeal — complete 2026 guide
| Criteria | Cashless Claim | Reimbursement Claim |
| Hospital requirement | Network / empanelled hospitals only | Any hospital with no restriction |
| Advance notice — planned admission | 48-72 hours before admission | Inform insurer within 24 hours of admission |
| Advance notice — emergency | 24 hours post-admission | 24 hours post-admission |
| Upfront payment | None except copay and non-covered items | Full bill paid at discharge from own funds |
| Document collection burden | Low — hospital handles most submissions | High — policyholder collects and submits all documents |
| Submission deadline | Pre-authorisation done before or at admission | 7-30 days post-discharge — check your policy |
| Processing time | 2-6 hours for pre-auth; immediate at discharge | 15-30 working days from receipt of full documents |
| Risk of partial approval | Lower — amounts agreed upfront before treatment | Higher — insurer may dispute line items post-payment |
| Best scenario | Planned surgery at a network hospital | Emergency at non-network; specialist not on network |
| Worst scenario | Emergency in an area with no network hospitals | Policyholder has insufficient savings to pay bill upfront |
We recommend cashless claims for all planned hospitalisations at network hospitals. The combination of zero upfront payment, low document burden, and pre-agreed settlement amounts makes it the superior option in every scenario where it is available. Use reimbursement only when cashless is unavailable — a non-network hospital or a necessary specialist not on the network list.
⚠️ WARNING: Missing Even One Document Restarts the Processing Clock
What happens: You submit 10 of 11 required documents. Your insurer issues a deficiency notice for the missing item. The 30-day processing timeline restarts from the date you submit the missing document — adding 6-8 weeks to your wait time. A missing discharge summary or prescription has this effect. What to do instead: Create a physical document folder at hospital admission. Collect every bill, prescription, and report on the same day it is issued. Photograph each document before handing over originals. Do not leave the hospital without the signed discharge summary.
Scenario 1: Meena, 37, School Principal — Planned Surgery Done Wrong (Hyderabad)
Meena needed appendix surgery and booked a private hospital without checking network status. The hospital was not on Star Health’s cashless list. She paid Rs 1,40,000 at discharge and filed a reimbursement claim. Star Health settled Rs 1,18,000 — Rs 22,000 was deducted for non-covered consumables and room rent above policy sub-limits. The process took 24 working days. Four cashless Star Health hospitals were within 5 km of the non-network hospital she chose. Verdict: Always verify network status before booking. One phone call to your TPA saves the full bill amount upfront.
Scenario 2: Ravi, 44, IT Manager — Emergency Accident, Non-Network (Bengaluru)
Ravi had a road accident and was taken by ambulance to the nearest hospital — a non-network facility. His wife paid Rs 85,000 at discharge. She filed a reimbursement claim within 5 days with a complete document set including the FIR, itemised bill, discharge summary, and all investigation reports. HDFC Ergo settled Rs 78,000 within 18 working days. The Rs 7,000 deduction covered non-medical items (telephone, guest food) excluded under the policy. Verdict: In genuine emergencies where cashless is impossible, reimbursement works well — but you need accessible savings and must retain every document from admission onwards.
Scenario 3: Priya, 52, HR Director — Specialist Not on Network (Mumbai)
Priya needed cardiac bypass surgery and insisted on a specific surgeon at Kokilaben Hospital — not on her HDFC Ergo cashless list but widely considered the best available for her condition. Surgery cost: Rs 4,80,000. She paid upfront, submitted a complete reimbursement claim, and received Rs 4,40,000 within 22 working days. The Rs 40,000 deduction covered items excluded under her policy sub-limits. Net out-of-pocket: Rs 40,000. Verdict: For life-critical surgery where specialist quality outweighs convenience, reimbursement is entirely valid. Confirm excluded items with your insurer before the surgery date.
Scenario 4: Ahmed, 29, Teacher — Cashless Done Correctly (Delhi)
Ahmed was diagnosed with typhoid requiring 5 days’ hospitalisation. He checked his Niva Bupa TPA portal — Apollo Hospital, 3 km away, was on the cashless list. He called the TPA 48 hours before planned admission, the hospital insurance desk submitted pre-authorisation, and his insurer approved Rs 64,000 within 4 hours. At discharge Apollo billed Niva Bupa directly. Ahmed paid Rs 2,500 for non-covered pharmacy items only. Total out-of-pocket on a Rs 64,000 bill: Rs 2,500. Verdict: Cashless done correctly delivers near-zero financial stress and near-zero paperwork. The one pre-admission check makes all the difference.
| Pros of Cashless | Cons of Cashless | Pros of Reimbursement | Cons of Reimbursement |
| Zero upfront payment — no financial stress at discharge | Available at network hospitals only — restricts hospital choice | Full freedom to choose any hospital or specialist | Full bill must be paid from your own funds at discharge |
| Hospital insurance desk handles most paperwork — minimal admin burden | Pre-authorisation can be denied or partially approved before treatment | Ideal when nearest or best specialist is not on the cashless network | Takes 15-30 working days to receive reimbursement after submission |
| Approved amount agreed before treatment — no post-payment disputes on approved items | Network hospitals may not include your preferred specialist | Only option during emergencies in areas with no network hospital | High document collection burden — one missing item delays entire claim |
| Settlement at discharge — no waiting for repayment | If pre-auth is denied mid-treatment, you must switch to reimbursement | Suitable for rural and remote areas with limited empanelled hospitals | Risk of partial settlement — insurer may dispute line items after payment |
| Widely available — major Indian insurers have 10,000-25,000+ network hospitals | Some network hospitals charge higher rates via insurer agreements | FIR protection for accident claims when you file immediately | Tight submission deadline — 7-30 days post-discharge depending on insurer |
Mistake 1: Not Checking Network Status Before Planned Admission
Why it happens: Policyholders assume their preferred hospital is automatically on the cashless list. What to do instead: Call your insurer’s TPA helpline or check the network hospital directory online 48 hours before any planned procedure. If the hospital is not on the network, either move to a network hospital or prepare your savings for a reimbursement claim.
Mistake 2: Failing to Notify the Insurer Within 24 Hours of Emergency Admission
Why it happens: In a medical emergency, families focus entirely on the patient. Paperwork feels secondary. What to do instead: Save your TPA helpline number and your policy number on your phone and on a laminated card in your wallet today. Designate one family member as the insurance contact for any hospitalisation. Most insurers allow 24 hours — missing this can result in cashless being denied even at a network hospital.
Mistake 3: Missing the Reimbursement Submission Deadline
Why it happens: Patients return home, focus on recovery, and forget the 7-30 day submission window. What to do instead: Set a phone calendar reminder for Day 1 after discharge with your exact submission deadline. Most policies require documents within 15-30 days of discharge. Check your specific policy document for the exact figure.
Mistake 4: Submitting an Incomplete Document Set
Why it happens: Policyholders collect the main hospital bill but forget individual prescriptions, investigation reports, or the discharge summary. What to do instead: Use the document checklist above as your physical hospital folder from day one. Photograph every document daily on your phone as backup before submitting originals to your insurer.
Mistake 5: Accepting a Partial Settlement Without Reading the Deduction Breakdown
Why it happens: Policyholders are relieved to receive any payment and do not read the settlement advice letter carefully. What to do instead: Read every line of the settlement letter. Each deduction must cite a specific policy clause. If any deduction lacks a valid policy basis, file a written grievance with your insurer within 15 days of the settlement date. Under IRDAI regulations, insurers must respond to grievances within 15 days.
| Your Situation | Our Recommendation |
| Planned surgery at a verified network hospital | ✅ Cashless — zero upfront payment; insurer settles directly; minimal hassle |
| Emergency at the nearest hospital regardless of network status | ✅ Get treatment first. If non-network, inform insurer within 24 hours and file reimbursement. |
| Preferred specialist is not on the cashless network | ✅ Reimbursement — specialist quality justifies the admin burden for complex procedures |
| You are in a rural area with no nearby network hospital | ✅ Reimbursement is your only option — ensure you have accessible savings to cover the bill |
| You have limited liquid savings (cannot pay bill upfront) | ✅ Cashless is essential — verify network hospitals and book there for all planned treatment |
| You want to avoid paperwork entirely | ✅ Cashless — hospital handles pre-authorisation and billing; your only task is handing over your insurance card |
| You are unsure whether the hospital is on the network | ✅ Call your TPA before booking — one call resolves everything and prevents a costly error |
| Your cashless pre-authorisation was denied or partially approved | ✅ Pay the bill and file reimbursement immediately — retain every document from admission onward |
💡 Tip: Save your TPA helpline number and a list of the 5 nearest network hospitals in your phone contacts right now — before you ever need them. In a medical emergency, searching for this information under stress costs precious time and money.
| Claim Type / Scenario | Processing Time | Your Upfront Cost | Notes |
| Cashless — planned surgery (pre-auth approved) | 2-6 hours pre-auth; settled at discharge | Copay + non-covered items only | Fastest and most convenient option |
| Cashless — emergency at network hospital | 24 hours post-intimation for approval | Copay + non-covered items only | Inform insurer within 24 hours of admission |
| Reimbursement — complete documents submitted | 15-30 working days from submission | Full bill paid at discharge | Complete document set achieves fastest turnaround |
| Reimbursement — incomplete documents (deficiency notice) | 30-60 working days | Full bill + extended waiting period | Each missing document restarts the processing clock |
| Reimbursement — disputed items under review | 45-90 working days | Full bill + extended wait | Submit a written grievance citing policy clauses |
| Regulatory escalation (IRDAI/FCA/state DOI) | 60-120 days | No cost — all regulators are free to approach | Use only after two internal grievance attempts have failed |
Star Health Insurance (India) — Largest Cashless Network
Why recommended: 14,000+ empanelled hospitals nationwide; direct cashless settlement without TPA intermediary for most claims; 24/7 claims helpline. Claim settlement ratio: 91.4% (IRDAI FY2024-25). Best for: Planned hospitalisations in metro and tier-2 cities.
Niva Bupa Health Insurance (India) — Fastest Reimbursement
Why recommended: 93.7% claim settlement ratio (IRDAI FY2024-25) — highest among major standalone health insurers; 15-working-day average reimbursement turnaround; dedicated claims app for digital document submission; 12,000+ network hospitals. Best for: Policyholders who travel frequently and may need non-network care.
Bupa (UK) — Best Cashless Direct Billing
Why recommended: Direct billing with 700+ UK private hospitals; no upfront payment at discharge; strong digital pre-authorisation via app. Rating: Defaqto 5 stars; 4.0/5 Trustpilot. Best for: UK private health insurance policyholders.
Aetna (US) — Best In-Network Direct Settlement
Why recommended: 91% first-submission approval rate; direct settlement with in-network providers — the US equivalent of the cashless model. Rating: A+ AM Best; 3.8/5 JD Power 2025. Best for: US health plan members seeking maximum in-network coverage.
We recommend Star Health (India) for the widest cashless coverage and Niva Bupa for the fastest reimbursement processing. UK and US policyholders should prioritise plans with direct billing arrangements — the cashless equivalent in Western markets.
In a cashless claim, your insurer pays the hospital directly — you pay nothing upfront except copays and non-covered items, and the claim is settled at discharge. It is available only at network hospitals. In a reimbursement claim, you pay the entire hospital bill at discharge and submit documents to your insurer for repayment within 15-30 working days. Cashless is faster and simpler; reimbursement gives you complete hospital choice.
No. Cashless claims are only available at hospitals empanelled on your insurer’s network. Check your insurer’s website, the TPA portal, or call the helpline before any planned admission to confirm network status. If the hospital is not empanelled, you must use the reimbursement process instead.
You need: the completed claim form, the original itemised hospital bill with hospital stamp, all payment receipts, the discharge summary signed by the treating doctor, all investigation reports (blood tests, X-rays, scans), prescriptions matched to pharmacy bills, doctor consultation receipts, and bank account details for NEFT transfer. For accident cases, also include the FIR or MLC report. Missing any document delays the entire claim.
Pre-authorisation for a planned cashless claim takes 2-6 hours from the time the hospital insurance desk submits the form. For emergency cashless claims, approval is typically issued within a few hours of intimation. Settlement with the hospital happens at discharge — you leave without paying the main bill. There is no waiting period for the policyholder after a successful cashless discharge.
A reimbursement claim with a complete and correct document set takes 15-30 working days from the date your insurer receives all documents. If documents are missing, the insurer issues a deficiency notice and the processing clock restarts from when you submit the missing item. Disputed claims can take 45-90 working days. Filing with a complete document pack on day one is the single most effective way to ensure a fast settlement.
If pre-authorisation is denied, you have two options: choose a network hospital where cashless approval can be obtained, or proceed at the current hospital and file a reimbursement claim after discharge. If the denial is incorrect, file an immediate written grievance with your insurer. Under IRDAI regulations, insurers must respond to grievances within 15 days. In the UK escalate to the Financial Ombudsman Service; in the US contact your state Department of Insurance.
No. Each hospitalisation uses one settlement method. If you are at a cashless network hospital, the claim is cashless. If you are at a non-network hospital, the claim is reimbursement. The only partial exception is when an insurer approves part of the bill cashlessly and you pay the remainder, then claim the non-covered items as a separate reimbursement — though this is uncommon.
A Third Party Administrator (TPA) is an IRDAI-licensed company that manages health insurance claims on behalf of your insurer. The TPA processes pre-authorisation requests, maintains the network hospital list, verifies documents, and handles reimbursement processing. Your insurance card shows your TPA’s helpline number — call it first for all claim queries. Some newer insurers such as Star Health and Niva Bupa now handle claims directly without a TPA intermediary.
No. Insurers can issue partial pre-authorisation — approving less than the estimated treatment cost. Common reasons include: the estimate exceeds your sum insured, some items fall under policy sub-limits or exclusions, or the insurer requires additional medical documentation. If pre-auth is partial, confirm with the hospital billing desk exactly what the approved amount covers before treatment proceeds, so there are no surprises at discharge.
Read the settlement advice letter in full — each deduction must specify the policy clause justifying it. If any deduction lacks a valid policy basis, file a formal written grievance with your insurer within 15 days of the settlement letter date. In India, escalate unresolved grievances to IRDAI’s Integrated Grievance Management System at igms.irda.gov.in. In the UK, escalate to the Financial Ombudsman Service. Keep all original documents — they are essential for any appeal.
This article is for informational purposes only. Always consult a licensed insurance professional before making coverage decisions. Trust My Policy does not sell insurance products or represent any insurer.

Jagadeesh Gutha is the founder of TrustMyPolicy.com, an independent insurance information platform covering life, health, car, home, and business insurance for US and UK readers. He researches insurance products, policy structures, and consumer rights to help everyday people make informed coverage decisions without the jargon. All content on TrustMyPolicy is independently researched, fact-checked, and written to educate — not to sell.
Insurance Guides for UK, USA & Worldwide We are not an insurer or broker.
Reader Comments (0)