
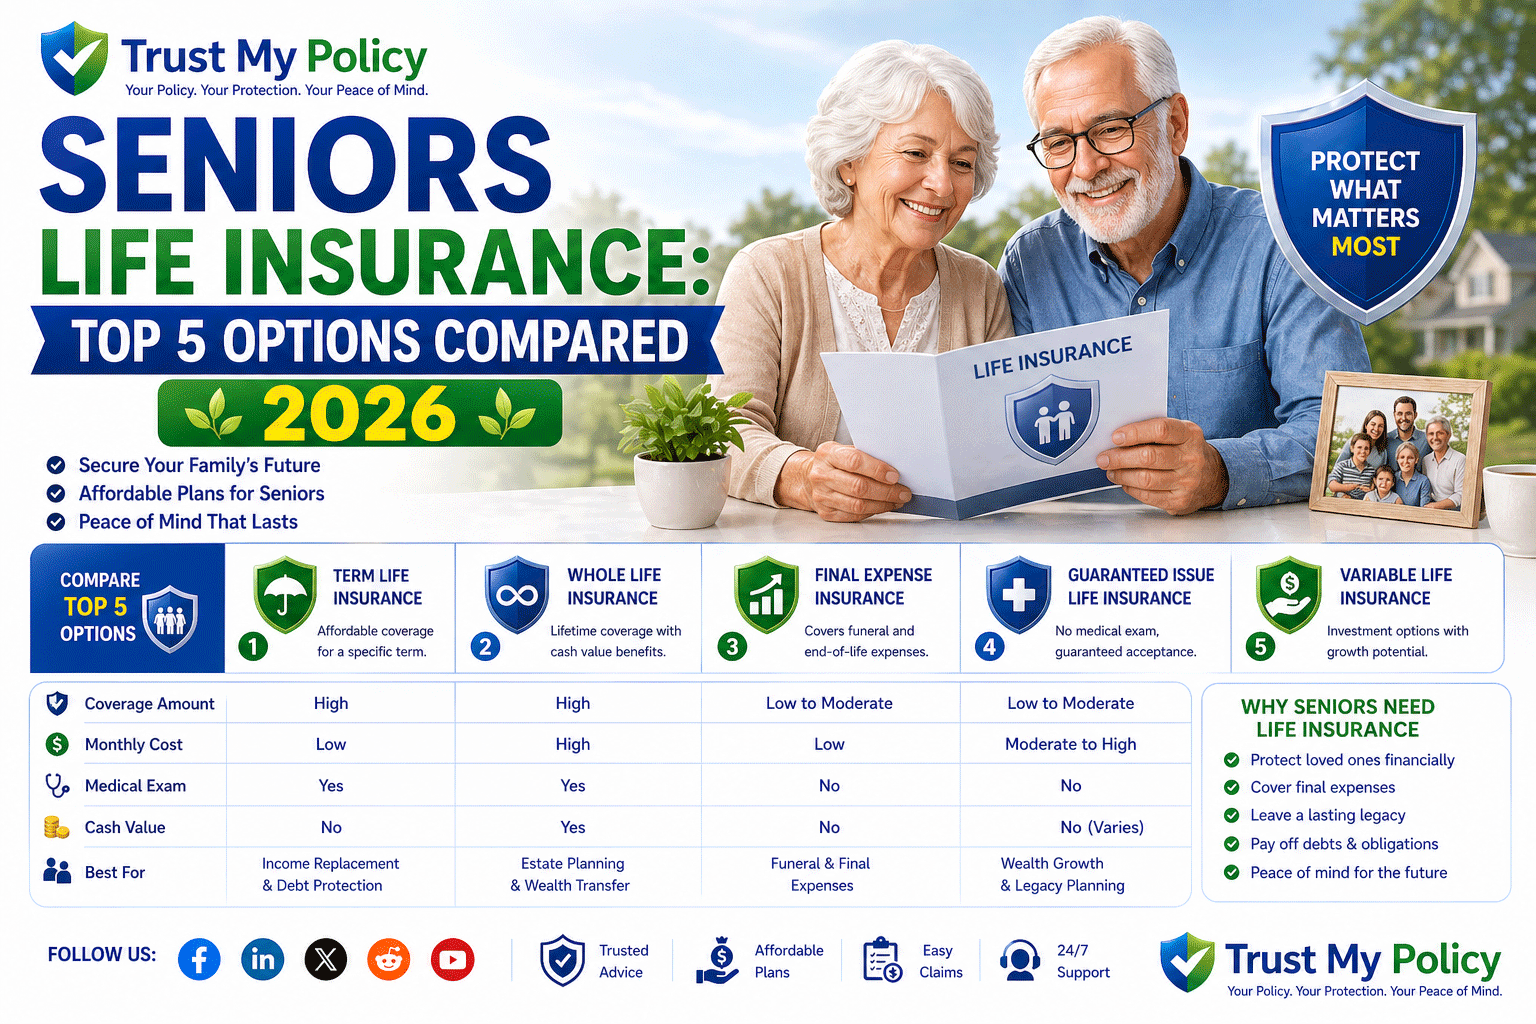
Seniors life insurance in 2026 covers three main options. UK: Over-50s plans (guaranteed acceptance, ages 50–85, £5,000–£20,000 cover, from £8/month, 2-year wait); term life (medically underwritten, cover up to age 90, from £50/month at age 60); whole life (permanent, best for IHT). USA: Guaranteed issue whole life (ages 45–85, up to $25,000, 2-year graded benefit); term life (Penn Mutual: $31/month for 65-yr-old woman, $100k, 10-year); GUL (permanent, most cost-effective for over-60s).
Margaret, 67, thought she had left it too late for life insurance. Her GP had flagged high blood pressure and early-stage type 2 diabetes. She assumed no insurer would touch her. In fact, she had three good options: an over-50s plan requiring no medical information, a whole life policy that would still accept her after underwriting, and a prepaid funeral plan. She chose an over-50s plan for £8,000 at £32/month. Her daughter will not need to worry about funeral costs.
Seniors life insurance in 2026 is more accessible than most people over 60 realise. The UK market for over-60s life cover includes guaranteed-acceptance over-50s plans, medically-underwritten term and whole life policies, and specialist options including funeral plans and gift inter vivos policies for inheritance tax planning. In the USA, options include guaranteed issue whole life, simplified issue, GUL policies, and senior-specific term life.
This guide covers every life insurance option available to seniors in the UK and USA in 2026 — with real costs, which health conditions affect eligibility, the best providers, and a decision framework for choosing the right policy at your age and health status.
| Feature | UK | USA |
| Best no-medical-exam option | Over-50s plan — guaranteed acceptance 50–85 | Guaranteed issue whole life — 45–85 |
| Coverage limit (no-exam) | Up to £20,000–£25,000 | Up to $25,000 |
| 2-year graded death benefit | Yes — most over-50s plans | Yes — all guaranteed issue policies |
| Average funeral cost (key trigger) | £4,141 (SunLife Cost of Dying 2024) | $9,000–$12,000 |
| Cheapest senior term life | From £50–£90/month (age 60, £150k, 10-yr) | Penn Mutual: $31/month (woman, 65, $100k, 10-yr) |
| Maximum entry age (term life) | Some providers to age 79–85 | Most cap at 70–75; some to 80 |
| Best IHT / estate planning tool | Whole life written in trust | Permanent life (whole life or GUL) |
| Regulated by | FCA; FSCS for UK policies | State insurance commissioners; NAIC |
Think of seniors life insurance like a financial gift to the people you love — one that arrives exactly when the money is most needed and most difficult to find. A £5,000 or $10,000 payout arrives weeks after death, exactly when your family is arranging a funeral and facing immediate costs.
Seniors life insurance is any life insurance policy designed for or accessible to people typically over age 50 or 60. It differs from standard policies in that it often offers guaranteed acceptance (no medical exam), smaller coverage amounts focused on final expenses, and policies that last for the rest of the holder’s life rather than a fixed term. The two most common triggers are: covering funeral costs and leaving a small legacy.
Who typically needs it: Retired adults aged 55–85 who want to ensure their funeral costs don’t burden their family, leave a small cash gift for children or grandchildren, cover any remaining debts or credit card balances, or reduce inheritance tax liability with a written-in-trust policy.
| Criteria | Over-50s Plan (UK) / Guaranteed Issue (USA) | Term Life (Senior) | Whole Life (Senior) |
| Medical exam required? | No — no questions, guaranteed acceptance | Yes — health questionnaire required | Yes — health questionnaire; exam may be required |
| Coverage amount | Up to £20k–£25k (UK) / $25k (USA) | Up to £150k–£500k+ (UK) / $1M+ (USA) | Up to £250k+ (UK) / unlimited (USA) |
| Coverage duration | Whole of life | Fixed term (10–20 years) | Whole of life |
| 2-year waiting period | Yes — graded death benefit applies | No — full cover from day one | No — full cover from day one (if health accepted) |
| Best for | Funeral costs, guaranteed acceptance regardless of health | Mortgage remaining, income replacement, defined need | Estate planning, IHT, guaranteed large legacy |
| Monthly cost (age 65, £/$/10k cover) | ~£28–£45/month (UK) / ~$60–$90/month (USA) | ~£30–£50/month (UK) / ~$50–$100/month (USA, $100k) | ~£100–£200+/month (UK) / $150–$300+/month (USA) |
| Winner | Best for health conditions and guaranteed need; worst value per £/$ of coverage | ||
| Provider | Why Recommended | Coverage Range | Key Feature |
| SunLife | UK’s most popular over-50s plan — Defaqto 5-star rated. No medical questions. Premiums stop at 90 (cover continues). Leading brand in the UK senior market. | £1,000–£18,000 | Premiums stop at 90; award-winning customer service |
| Aviva | Strong brand, DigiCare+ health app included, funeral payment pledge. Over-50s plan with immediate funeral payment option. | Up to £25,000 | Funeral Payment Pledge — immediate £5,000 for funeral costs while rest of claim is processed |
| Royal London | UK’s top-rated life insurer (2026). Strong whole life and term options for seniors in good health. Helping Hand support service. | Flexible — from £10,000 | Highest overall claims rate (98.8% in 2024) |
| Legal & General | Cheapest term life quotes for many senior profiles. Moneyfacts 6-time winner. Simple online application. | From £100,000+ (term) | Cheapest term life for many 60–70 age profiles |
| British Seniors Insurance Agency | Specialist in over-50s insurance. Simple application, no medical exam, competitive for the guaranteed market. | Up to £20,000 | Specialist focus on the senior market; straightforward process |
| Provider | Why Recommended | AM Best | Best For |
| Penn Mutual | Cheapest term life for women aged 60–70. $31/month for a 65-year-old woman for $100,000 10-year term. Mutual insurer with strong financial record. | A+ (Superior) | Cheapest senior term life; women 60–70 |
| John Hancock | Cheapest term life for senior men. Most affordable for men over 70. Vitality wellness programme offers premium discounts. | A+ (Superior) | Cheapest for senior men; active lifestyle rewards |
| State Farm | Lowest rates for smokers over 60. Strong J.D. Power rating. No cancellation fees. Broad senior product range. | A++ (Superior) | Senior smokers; customer satisfaction; bundling |
| Physicians Mutual | Best guaranteed acceptance (no medical exam) for seniors. Simplified and guaranteed issue options. Well-reviewed for claims service. | A (Excellent) | Guaranteed issue; no medical exam; serious health conditions |
| Pacific Life | Over 150 years in business. $1.5 trillion in policies in force. GUL with no-lapse guarantee to age 90 or 121. 14 senior policy types. | A+ (Superior) | GUL and universal life; high coverage amounts; complex needs |
We recommend SunLife for most UK seniors seeking funeral cover without a medical exam, and Penn Mutual for USA senior women, John Hancock for USA senior men, seeking the most affordable term life. For those with health conditions, Physicians Mutual (USA) and SunLife or Aviva (UK) offer guaranteed acceptance.
Over-50s plan with SunLife: £8,000 coverage, no medical questions. Cost: £32/month. Covers estimated funeral cost of £4,141 with £3,859 remaining as a gift for her daughter. Two-year graded period applies — accidental death covered from day one, natural causes covered in full from year 3 onwards. Best decision: buy this year, not next — every year of delay increases the premium.
Whole life policy written in trust with Royal London: £200,000 coverage. Purpose: cover potential IHT liability on estate valued at £800,000 (£325,000 threshold + £175,000 RNRB leaves £300,000 potentially taxable = £120,000 IHT). Cost: approximately £380/month at age 62, good health. Policy held in trust — payout bypasses estate, pays IHT bill directly. Beneficiaries don’t wait for probate.
Linda is 70, recently retired, and previously covered by her employer’s group life insurance. Now uncovered. She wants $15,000 to cover funeral costs. Physicians Mutual guaranteed issue whole life: $15,000 coverage, no medical exam. Cost: approximately $85–$100/month. Two-year graded benefit applies. Best option given her age and potential health conditions — no risk of being declined.
Harold wants $250,000 of term life for 10 years while his wife transitions to full Social Security income. Penn Mutual: $250,000, 10-year term. Cost: approximately $180/month at age 63. Full coverage from day one, no waiting period. Better value than guaranteed issue or GUL for this defined-period need.
Over-50s plans guarantee acceptance for ages 50–85 (UK) and 45–85 (USA). Even at age 80, a senior can take out a guaranteed issue policy covering funeral costs. The only thing that changes with age is cost — it rises every year you wait.
| ⚠️ WARNING: The 2-Year Graded Benefit Is Not a Small Print Issue
On over-50s and guaranteed issue policies, death from natural causes in the first 2 years pays back premiums plus interest — NOT the full face value. If Margaret buys a £8,000 plan and dies 14 months later, her daughter receives approximately £560 (14 months × £32 + interest) — not £8,000. This is the most significant limitation of these policies and must be fully understood before buying. If you need immediate full coverage, a medically underwritten term or whole life policy (subject to health acceptance) provides full benefit from day one. |
Over-50s plans are expensive per £/$ of coverage because no medical information is collected — the insurer prices for average health, not your individual health. A 65-year-old in good health gets significantly more coverage for the same premium with a medically underwritten term or whole life policy. Only choose over-50s plans if your health would prevent you from getting better cover.
A UK life insurance payout passing through your estate faces a 6–12 month probate delay and potential 40% IHT. Writing in trust costs nothing and takes 10 minutes. It means your family gets the money in weeks, not months or years, and it doesn’t count toward your taxable estate.
For the full comparison of life insurance types, see our what is the best life insurance policy guide. For seniors considering no-exam options specifically, our no medical life insurance article covers all guaranteed and simplified issue options.
| 📋 Disclaimer
This article is for informational purposes only. Always consult a licensed insurance professional before making coverage decisions. Trust My Policy does not sell insurance products or represent any insurer. |

Jagadeesh Gutha is the founder of TrustMyPolicy.com, an independent insurance information platform covering life, health, car, home, and business insurance for US and UK readers. He researches insurance products, policy structures, and consumer rights to help everyday people make informed coverage decisions without the jargon. All content on TrustMyPolicy is independently researched, fact-checked, and written to educate — not to sell.
Insurance Guides for UK, USA & Worldwide We are not an insurer or broker.
Reader Comments (0)