
When Tom Bradley, 36, from Manchester applied for a mortgage on a three-bedroom semi-detached, his broker asked one question he hadn’t prepared for: ‘Have you sorted your life insurance yet?’ Tom hadn’t. He assumed it would be expensive, complicated, or require a lengthy medical. Forty minutes later — having compared quotes online — he had a £500,000 level term policy with Legal & General. His monthly premium: £14.
Tom’s story is increasingly common. UK consumers are more aware than ever that term life insurance is far more affordable than most people expect — yet millions of households remain unprotected. According to the Association of British Insurers (ABI), roughly 8.4 million families in the UK would face serious financial difficulty within a year if the main earner died. If you’re in that group, this guide will help you fix that today.
| Provider | Best For | Starting At | Our Rating |
| Legal & General | Lowest premiums in the UK market | From £8/mo | ★★★★★ |
| Aviva | Fast online approval + trusted brand | From £9/mo | ★★★★★ |
| Royal London | Mutual insurer — profits shared with members | From £10/mo | ★★★★★ |
| LV= | Top-rated customer service and claims | From £9/mo | ★★★★★ |
| Vitality | Earn rewards and premium discounts | From £11/mo | ★★★★½ |
Important: All providers listed are FCA-regulated. Premiums shown are sample estimates for a healthy non-smoking applicant aged 30–35. Your actual premium depends on age, health, smoking status, coverage amount, and term length. Always compare personalised quotes.
New to life insurance? Our guide to how life insurance works explains the basics in plain language.
Term life insurance in the UK works simply: you pay a monthly premium for a fixed term — typically 10 to 40 years. If you die during the term, your insurer pays a lump sum (the sum assured) to your beneficiaries. If you outlive the term, the policy ends with no payout.
There are two main types of term cover available in the UK:
Level term: The payout stays the same throughout the policy term. Ideal for protecting family income or leaving a fixed inheritance. If you take out £300,000 of level term cover, your family receives £300,000 whether you die in year 1 or year 25.
Decreasing term: The payout reduces over time, roughly in line with a repayment mortgage balance. Significantly cheaper than level term and specifically designed for mortgage protection. Most lenders recommend this type to accompany a repayment mortgage.
The UK term life market is heavily regulated by the Financial Conduct Authority (FCA). This means all providers must meet strict financial soundness requirements, treat customers fairly, and pay valid claims — giving UK consumers stronger protections than many global markets.
| Provider | Policy Type | Monthly Premium | Defaqto | Max Age | Best For |
| Legal & General | Level / Decreasing | £8–£25/mo | 5 Stars | 77 | Lowest premiums |
| Aviva | Level / Decreasing | £9–£28/mo | 5 Stars | 75 | Online convenience |
| Royal London | Level / Decreasing | £10–£30/mo | 5 Stars | 75 | Mutual benefits |
| LV= | Level / Decreasing | £9–£27/mo | 5 Stars | 75 | Customer service |
| Zurich | Level / Decreasing | £10–£32/mo | 5 Stars | 74 | Terminal illness cover |
| AIG Life | Level / Decreasing | £8–£26/mo | 4 Stars | 77 | High coverage |
| Vitality | Level / Decreasing | £11–£35/mo | 5 Stars | 75 | Rewards & discounts |
| Scottish Widows | Level / Decreasing | £9–£29/mo | 5 Stars | 74 | Flexible cover |
Over 50 and looking for cover? Our dedicated guide to life insurance for seniors covers UK and global options.
Founded: 1836 | Defaqto Rating: 5 Stars | FCA Registered: YES | UK Claims Paid: 97.3%
Legal & General is the UK’s largest term life insurer by market share and consistently offers the most competitive premiums in the market. Their term life policies start from just £8/month for young, healthy applicants — making quality protection genuinely accessible. Their 2024 claims data shows a 97.3% payout rate on term life claims, one of the highest in the industry.
Their online application process takes under 20 minutes for most applicants, with instant decisions available for straightforward cases. No GP report is required for policies under £500,000 for applicants under 45 with no significant health history — a genuine time-saver compared to older application processes.
Premium example: Male, 35, non-smoker, £500,000 level term, 25 years — approximately £18–£22/month.
Our verdict: The default first choice for most UK buyers. Start here for your comparison baseline.
Founded: 2000 (origins 1696) | Defaqto: 5 Stars | FCA Registered: YES
Aviva is the UK’s most recognised insurance brand and one of the most trusted names in financial services. Their online portal is genuinely excellent — applying takes under 15 minutes and many policies are issued instantly without human underwriting intervention. Their MyAviva app allows policyholders to manage coverage, update beneficiaries, and access policy documents 24/7.
Aviva includes terminal illness benefit as standard on all term policies at no extra cost — if you’re diagnosed with a terminal illness with less than 12 months to live, you can claim your full sum assured immediately. This is now standard across most UK providers but Aviva’s implementation is particularly clean.
Premium example: Female, 32, non-smoker, £300,000 level term, 20 years — approximately £9–£13/month.
Our verdict: Best choice for buyers who value brand recognition and want the most polished digital insurance experience in the UK market.
Founded: 1861 | Defaqto: 5 Stars | FCA Registered: YES
Royal London is the UK’s largest mutual life insurer — meaning it’s owned by its policyholders, not shareholders. This structure means profits are reinvested for members rather than distributed to external investors. In practice, this often translates to competitive premiums, strong claims payouts, and genuine long-term alignment with policyholder interests.
Royal London was named Protection Insurer of the Year at the 2024 Cover Excellence Awards. Their Waiver of Premium benefit — which keeps your policy active if you’re unable to work due to illness or injury — is available as an affordable rider and is one of the best implementations in the market.
Premium example: Male, 38, non-smoker, £400,000 level term, 22 years — approximately £22–£28/month.
Our verdict: Best for buyers who want a trusted mutual insurer with a genuine long-term customer focus.
Founded: 1843 | Defaqto: 5 Stars | Trustpilot: 4.3/5
LV= (Liverpool Victoria) consistently ranks among the highest-rated UK insurers for customer service and claims handling. Their Trustpilot score of 4.3/5 from thousands of verified reviews reflects a genuine service culture rather than marketing positioning. Their term life policies include fracture cover and hospitalisation benefits as optional extras — making them particularly attractive for families who want comprehensive protection at a reasonable monthly cost.
Our verdict: Best for buyers who prioritise claims experience and customer service over getting the absolute cheapest premium.
Founded: 1872 | Defaqto: 5 Stars | FCA Registered: YES
Zurich’s terminal illness definition is notably broader than many competitors — they pay out when life expectancy is less than 12 months, but also include several specific conditions that automatically trigger the benefit regardless of life expectancy. This broader definition means fewer disputed claims and faster payouts for policyholders in difficult circumstances.
Our verdict: Best for buyers who want the most comprehensive terminal illness protection available in the UK market.
Defaqto: 4 Stars | FCA Registered: YES
AIG Life offers highly competitive rates for high sum assured policies (£750,000+) and extends coverage to age 77 — one of the longest age limits for term cover in the UK market. For professionals in their 40s seeking large coverage amounts, AIG’s pricing is frequently the most competitive available.
Our verdict: Best for buyers seeking £750,000+ in coverage who want the most competitive pricing at higher sum assured levels.
Defaqto: 5 Stars | FCA Registered: YES
Vitality’s model is unique in the UK market: the more health-conscious behaviours you demonstrate (tracked via Apple Watch, fitness apps, or health assessments), the lower your premiums become over time. Annual premium discounts of up to 40% are achievable for highly active policyholders. Vitality also offers free cinema tickets, discounted gym memberships, and health monitoring tools as part of their membership.
Our verdict: Best for health-conscious buyers aged 25–45 who will actively engage with the rewards programme to earn significant discounts.
Part of: Lloyds Banking Group | Defaqto: 5 Stars | FCA Registered: YES
Scottish Widows offers one of the most flexible term policy structures in the UK — policyholders can increase cover at key life events (marriage, birth of a child, house purchase) without new medical underwriting. This guaranteed insurability option is particularly valuable for younger buyers whose coverage needs will grow over time.
Our verdict: Best for buyers in their late 20s or 30s who expect their coverage needs to grow significantly and want flexibility built into their policy.
Not sure whether term or whole life is right for you? Read our whole life vs term life comparison.
Emma just completed on her first property in Birmingham. Her mortgage broker strongly recommended mortgage protection cover. She wants the simplest, most affordable option to protect her repayment mortgage.
Best option: Legal & General decreasing term, £250,000, 25 years. The sum assured reduces in line with her mortgage balance. Approximate cost: £8–£12/month — significantly cheaper than level term for the same initial coverage amount.
James and Sarah have two young children and a joint income. If either died, the surviving partner would struggle to maintain the mortgage and cover childcare costs on one salary.
Best option: Two separate level term policies — Royal London or Aviva — each for £400,000, 30 years. Joint policies pay out only once (on the first death). Separate policies provide double the protection. Combined cost: approximately £25–£35/month.
Michael earns £75,000/year as a contractor with no employer death-in-service benefit. He wants comprehensive income replacement for his family if he dies in the next 20 years.
Best option: LV= level term, £750,000, 20 years, with waiver of premium rider. Approximate cost: £45–£55/month. The waiver rider keeps his policy active if a health condition prevents him from working.
Priya runs five times a week, tracks her health data, and wants her insurance premiums to reflect her healthy lifestyle rather than paying standard rates.
Best option: Vitality term life. Starting premium slightly higher than Legal & General, but with active engagement Priya could earn discounts of 20–40% within 12 months — making her effective premium the cheapest available.
Pro Tip: Always buy through an FCA-regulated broker if you’re unsure which policy to choose. Whole-of-market brokers compare every provider and are required by law to recommend the most suitable product for your circumstances — not just the one that pays the highest commission.
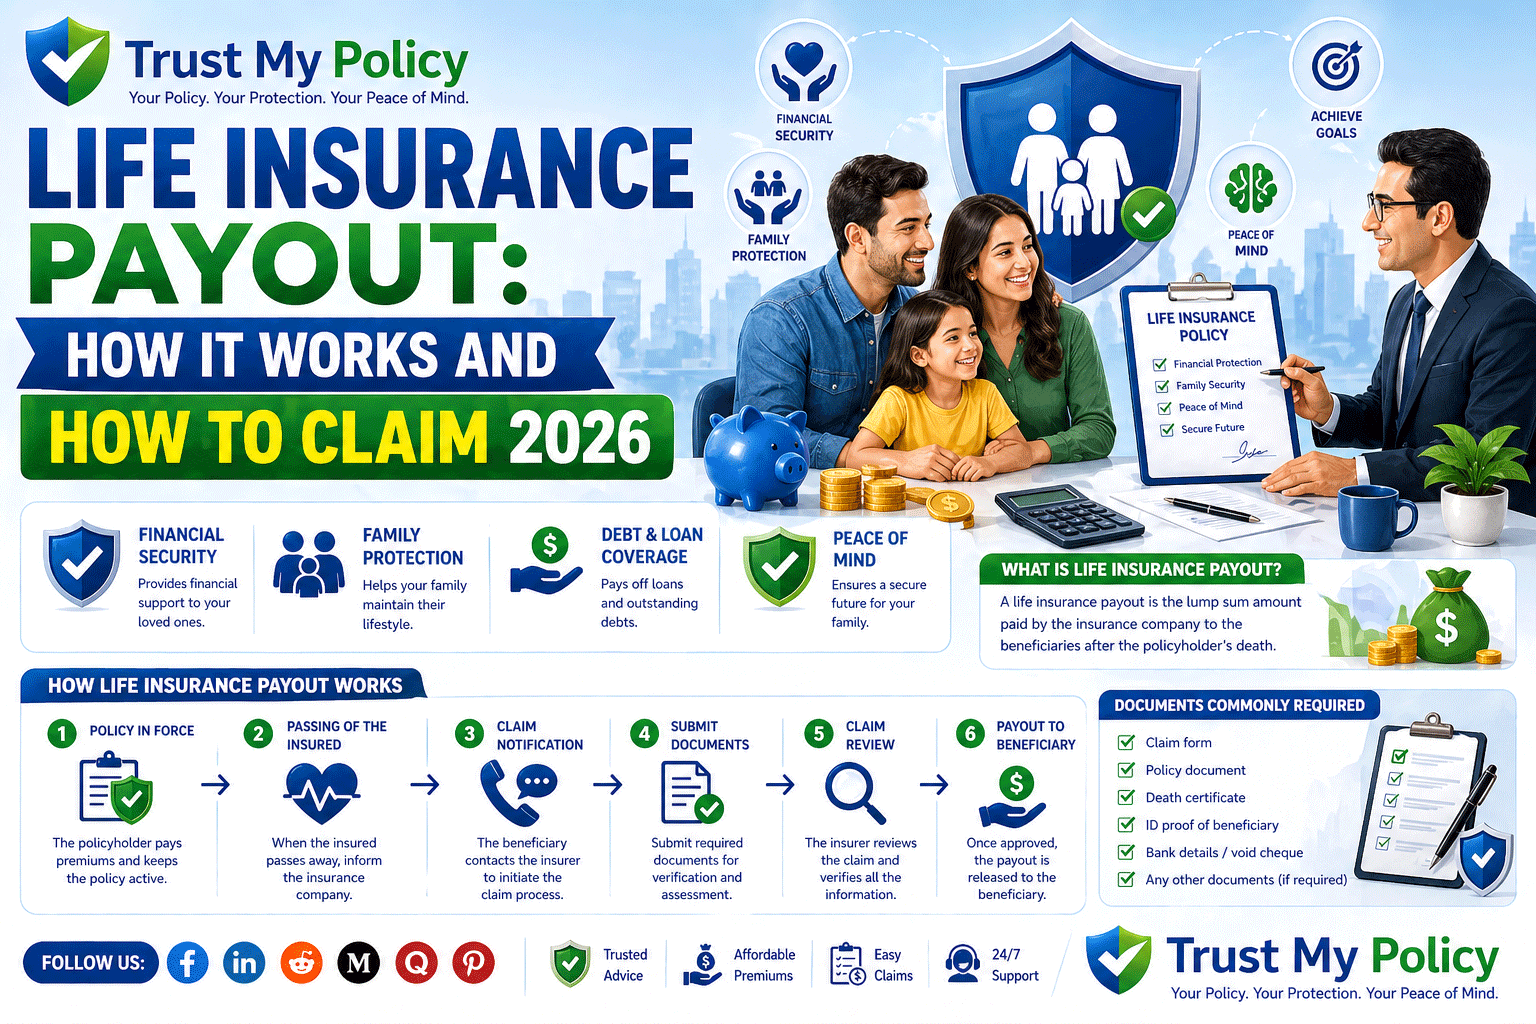
Once you have a policy, make sure your family knows how the insurance claim process works.
A joint policy is cheaper monthly but pays out only once — on the first death. After the first claim, the surviving partner has no cover. Two separate policies cost slightly more but provide twice the protection. For couples with dependants, separate policies are almost always the better choice.
Decreasing term is designed specifically for mortgage protection, where the amount you need reduces over time. Using it to protect family income is a mistake — your family’s income need doesn’t decrease as years pass. Use level term for income replacement.
You’re far more likely to be diagnosed with a serious illness during your working life than to die. Critical illness cover pays out a lump sum on diagnosis of specified conditions — cancer, heart attack, stroke, and many others. Many UK providers offer combined life and critical illness policies at strong value.
Writing your life insurance policy in trust means the payout goes directly to your beneficiaries without going through your estate. This avoids inheritance tax on the payout and significantly speeds up payment. It’s free to do and most UK insurers provide the trust forms. Not doing it is a genuinely costly omission.
According to ABI data, the average UK household is underinsured by approximately £230,000. The most common reason: people choose a coverage amount based on what seems affordable rather than what their family actually needs. Calculate your real number first, then find the most affordable policy for that amount.
Had another child? Remortgaged? Got a significant pay rise? Your insurance needs change at every major life event. Review your coverage at each milestone and increase your sum assured if needed. Scottish Widows and Royal London offer guaranteed insurability options that make this straightforward.
The cheapest premium is worthless if the insurer disputes or delays valid claims. Always check a provider’s claims paid percentage — Legal & General’s 97.3%, Aviva’s 98.1%, and LV=’s 97.7% are the benchmarks to compare against.
For a broader breakdown of what your policy covers, see our life insurance policy guide.
Legal & General is our top overall pick for 2026 — lowest premiums, 97.3% claims rate, and 5-star Defaqto rating. Aviva is the best for digital experience and brand trust. Royal London is the best mutual insurer. The best provider for you depends on your specific age, health, and coverage requirements.
For a healthy 35-year-old non-smoker, £500,000 of 25-year level term cover typically costs £18–£28/month depending on the provider. Smokers pay roughly double. Women typically pay 10–15% less than men of the same age. Get personalised quotes from at least three providers before deciding.
Yes. All UK term life insurance providers must be authorised and regulated by the Financial Conduct Authority (FCA). Always verify a provider’s FCA registration at fca.org.uk before purchasing. FCA regulation gives UK consumers strong rights including a 14-day cooling-off period.
Level term pays the same sum throughout the policy. Decreasing term pays a reducing amount designed to match a repayment mortgage balance. Decreasing term is cheaper. Level term is better for income replacement or leaving a fixed inheritance. Most buyers with a repayment mortgage use decreasing term for mortgage protection and a separate level term policy for family income protection.
Yes, in almost all cases. Writing your policy in trust means the payout bypasses your estate, avoiding inheritance tax and dramatically speeding up payment to your beneficiaries. It’s free to do, takes under 30 minutes, and is one of the most important steps most policyholders skip.
Often yes, depending on the condition and its management. Conditions like well-controlled Type 2 diabetes, managed hypertension, and some historical cancers can still qualify for cover — sometimes at standard rates, sometimes with a loading (higher premium). An independent whole-of-market broker is the best resource for finding the most accessible insurer for your specific health history.
Your next step: Compare at least three personalised quotes before buying. Writing your policy in trust is free and takes 30 minutes — make sure you do it. And always verify your provider’s FCA registration before purchasing.
Disclaimer:
This article is for educational purposes only. Trust My Policy is an independent informational platform and does not sell insurance products or represent any insurance provider. Readers should consult official policy documents or licensed professionals for personalized advice.

Jagadeesh Gutha is the founder of TrustMyPolicy.com, an independent insurance information platform covering life, health, car, home, and business insurance for US and UK readers. He researches insurance products, policy structures, and consumer rights to help everyday people make informed coverage decisions without the jargon. All content on TrustMyPolicy is independently researched, fact-checked, and written to educate — not to sell.
Insurance Guides for UK, USA & Worldwide We are not an insurer or broker.
Reader Comments (0)