
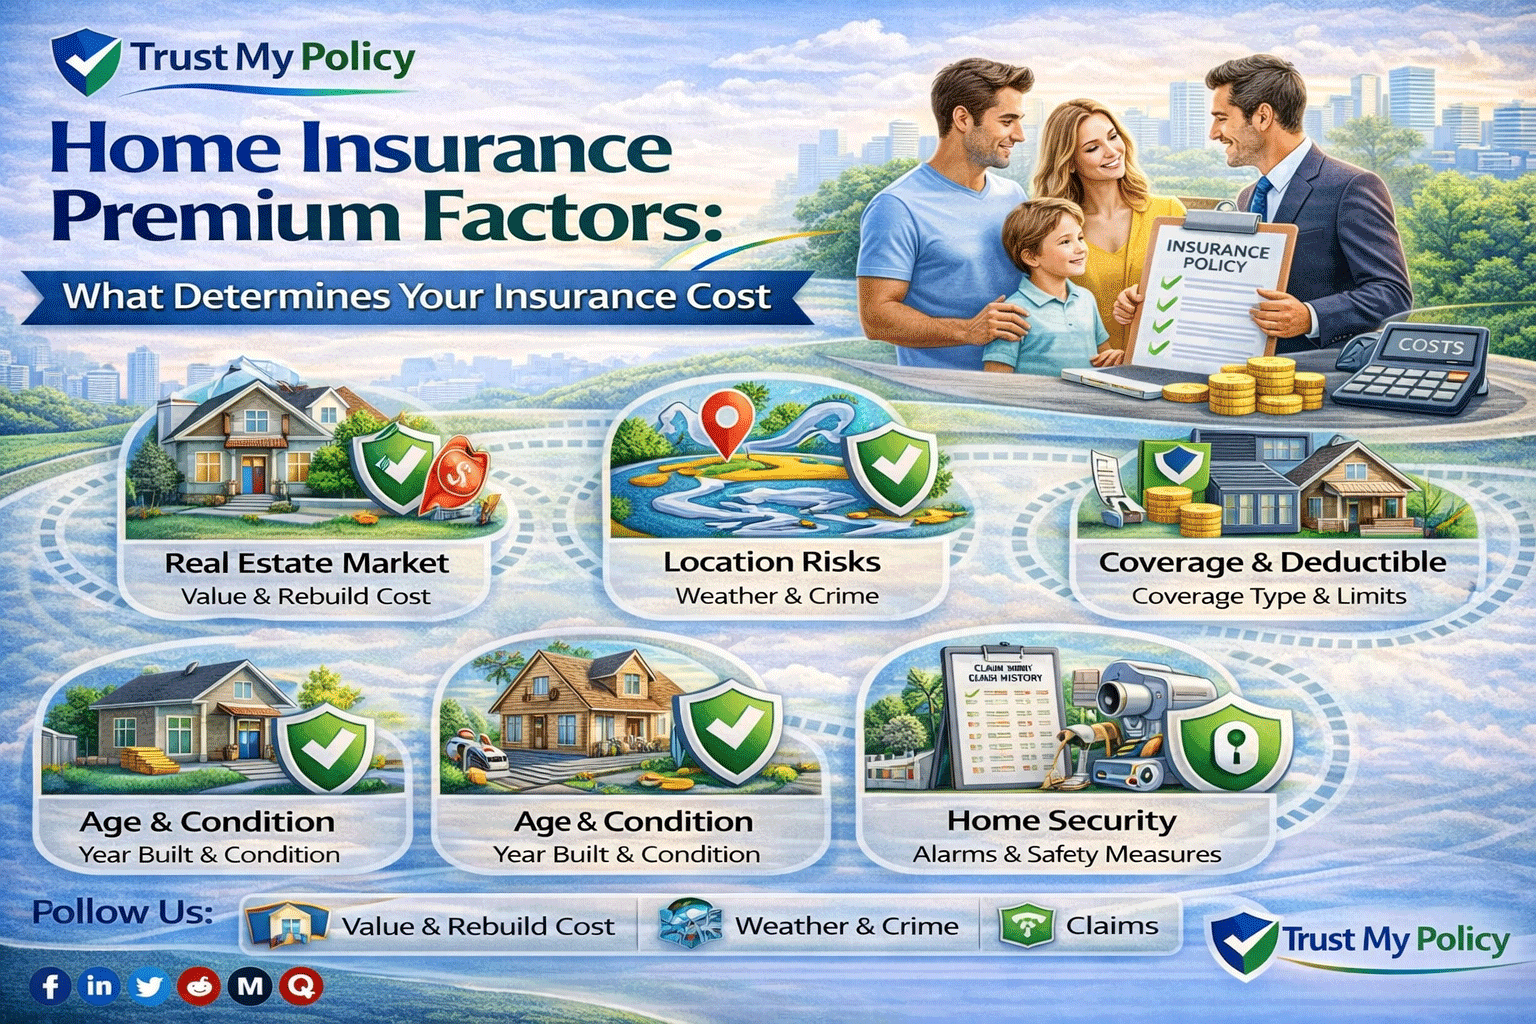
Home insurance premiums are driven by roof age and material, your home’s claims history (tracked via a CLUE report), distance to the nearest fire hydrant or station, construction type and age, security and safety features, and specific risk factors like swimming pools or certain dog breeds. A roof over 20 years old can raise your premium significantly compared to a newer roof, even on an identically valued home.
Brenda Coletti, 55, was quoted a surprisingly high home insurance premium in Tampa and assumed it was simply regional pricing, until her broker pulled her home’s CLUE report and pointed out her 22-year-old roof was the single largest factor driving her rate above her neighbors’ similar-sized homes.
Home Insurance Premium Factors in 2026 go well beyond home value and location. Roof age and material, your home’s claims history (tracked through a CLUE report), distance to the nearest fire hydrant or station, construction type, security features, and even certain dog breeds or swimming pools can all move your premium significantly. This guide breaks down exactly which factors matter most and what you can realistically influence.
This article covers the specific factors that drive home insurance pricing, what a CLUE report actually reveals, real scenarios with dollar figures, and what you can do to lower your premium. By the end, you’ll understand exactly why your quote looks the way it does.
| Feature | Details |
| What it is | The specific factors insurers use to calculate your home insurance premium |
| Who it affects | Every homeowner shopping for or renewing a home insurance policy |
| Major cost factors | Roof age/material, claims history (CLUE report), fire department distance, construction type, security features |
| Typical impact of an old roof | Can raise premiums significantly compared to a newer roof of similar home value |
| Key benefit | Understanding these factors helps identify what you can realistically improve |
| Key limitation | Some factors, like distance to a fire station, are fixed and can’t be changed |
| Regulator | State insurance departments (US); Financial Conduct Authority (UK) |
Think of your home insurance premium like a health insurance premium for your house, where specific “health indicators” – the roof’s age, the home’s claims history, the neighborhood’s fire protection – all factor into the final number, much like a person’s age, health history, and lifestyle factor into their own insurance pricing.
Home insurance premiums are calculated using a combination of home-specific risk factors: your roof’s age and material, your home’s claims history as recorded in a CLUE (Comprehensive Loss Underwriting Exchange) report, your distance to the nearest fire hydrant or station, your home’s construction type and age, and specific risk-increasing features like swimming pools or certain dog breeds. Anyone shopping for or renewing home insurance benefits from understanding which of these factors is actually driving their specific quote.
| Criteria | Factors That Raise Your Premium | Factors That Lower Your Premium |
| Roof | Older roof (15-20+ years), weather-prone materials | Newer roof, impact-resistant materials |
| Claims history | Multiple past claims on the property (CLUE report) | Clean claims history on the property |
| Safety features | Lack of smoke detectors, security system, updated wiring | Monitored security system, updated electrical and plumbing |
| Specific risks | Swimming pool, trampoline, certain dog breeds | None of these risk-increasing features present |
| Pros of understanding this | Helps you anticipate and budget for your actual quote | Helps you identify realistic ways to lower your premium |
We recommend reviewing your home’s CLUE report and roof age specifically for most readers, since these two factors are among the most significant and most commonly overlooked drivers of a higher-than-expected premium.
Scenario 1: Brenda, 55, homeowner in Tampa. Brenda’s 22-year-old roof was the single largest factor driving her premium above her neighbors’ rates, despite her home’s similar value. Verdict: roof age can outweigh home value as a premium driver. Action: Brenda replaced her roof and saw a meaningful premium reduction at her next renewal.
Scenario 2: A homeowner in Leeds who pulled his own home’s claims history before shopping for a new policy. He discovered a previous owner’s water damage claim still appeared in his property’s history, affecting his quotes from several insurers. Verdict: claims history follows the property, not just the current owner. Action: he provided context about the previous owner’s claim to several insurers, which helped clarify his own genuinely clean ongoing history.
Scenario 3: A homeowner in rural Texas living 12 miles from the nearest fire station. Her premium reflected this distance as a meaningful risk factor, significantly higher than a similar home located near a fire station in town. Verdict: fire protection distance is a real, often overlooked premium factor. Action: she compared quotes specifically from insurers known to weight this factor less heavily for rural properties.
Scenario 4: A homeowner in Houston with a swimming pool and an aggressive dog breed listed on several insurers’ risk lists. Both factors added a noticeable liability surcharge to her premium compared to a similar home without these specific risks. Verdict: certain home features carry a specific, quantifiable premium impact beyond general home value. Action: she added a pool safety fence and compared quotes from insurers with less restrictive dog breed policies.
| Pros | Cons |
| Understanding these factors helps you identify what’s actually driving your quote. | Some factors, like fire station distance, are fixed and outside your control. |
| Replacing an old roof can meaningfully lower your premium going forward. | A roof replacement is a significant upfront cost to realize this benefit. |
| Reviewing your home’s CLUE report can clarify confusing quote differences. | Claims history follows the property, which can affect you even from a previous owner’s claim. |
| Adding safety features like security systems can directly reduce your premium. | Specific risk factors like certain dog breeds can limit your insurer options entirely. |
| Comparing quotes across insurers can reveal different weightings for the same factors. | Understanding the full calculation takes more effort than comparing a single premium number. |
⚠️ WARNING: Never assume your home insurance premium is purely based on your home’s value and location. Specific factors like roof age, claims history, and even certain dog breeds can significantly move your premium independent of your home’s overall value.
| Your Situation | Our Recommendation |
| You don’t know your roof’s exact age | Yes — confirm this before requesting quotes, since it’s a major premium factor |
| You’ve never reviewed your home’s CLUE report | Yes — request it directly, especially if your quote seems unexpectedly high |
| You’re buying a home with an unknown claims history | Yes — review the property’s CLUE report as part of your purchase due diligence |
| You have a security system, updated wiring, or other safety features | Yes — ask your insurer about specific discounts for each one |
| You have a swimming pool, trampoline, or certain dog breed | Yes — compare quotes across insurers, since risk weighting varies for these factors |
| Your roof is over 15-20 years old | Yes — consider whether a replacement could meaningfully lower your long-term premium |
| You live far from the nearest fire station | Yes — compare quotes from insurers known to weight this factor differently |
💡 TIP: The single golden rule for home insurance premium factors: confirm your roof’s age and request your home’s CLUE report before shopping for quotes, since these two factors are among the most significant and most commonly overlooked.
| Scenario | Premium Factor | Effect on Premium |
| Roof under 10 years old | Newer roof | Baseline or discounted premium |
| Roof 20+ years old | Older roof | Can raise premium by 20%-50% or limit insurer options |
| Clean CLUE report, no prior claims | Favorable claims history | Baseline or discounted premium |
| Multiple prior claims on CLUE report | Unfavorable claims history | Can raise premium by 15%-40% |
| Home 12+ miles from nearest fire station | Distance to fire protection | Can raise premium by 10%-30% in rural areas |
| Monitored security system installed | Safety feature discount | Can lower premium by 5%-15% |
| Swimming pool present | Specific liability risk factor | Can raise premium by 5%-15% and add liability considerations |
LexisNexis CLUE Report (US) — The primary source for your home’s claims history report, used by most US insurers in underwriting. Cost range: free annual report available to homeowners. Best for: US homeowners wanting to review their property’s claims history. Rating: industry-standard claims history database.
Independent insurance brokers — Brokers can identify which specific factors are driving your quote and compare how different insurers weight them. Cost range: typically free for the consumer. Best for: any homeowner wanting a clear breakdown of their specific premium factors. Rating: varies by broker, check state or FCA licensing.
Licensed roofing contractors — Can provide an accurate assessment of your roof’s age, material, and condition relevant to your insurance quote. Cost range: often free for an initial inspection. Best for: homeowners unsure of their roof’s exact age or condition. Rating: varies by contractor, check local licensing.
NAIC consumer resources (US) — Publishes plain-language guidance on the factors that influence home insurance pricing. Cost range: free public resource. Best for: US consumers researching premium factors. Rating: regulatory standards body.
Insurance Information Institute (US) — Offers educational resources specifically explaining how factors like roof age and claims history affect home insurance pricing. Cost range: free public resources available. Best for: readers wanting deeper educational context. Rating: industry trade association resource.
We recommend requesting your home’s CLUE report and confirming your roof’s exact age as best overall first step, since these two factors are consistently among the most significant and most overlooked drivers of home insurance pricing.
Home insurance premiums are driven by roof age and material, your home’s claims history (via a CLUE report), distance to fire protection, construction type, safety features, and specific risk factors like swimming pools or certain dog breeds.
A CLUE (Comprehensive Loss Underwriting Exchange) report tracks insurance claims associated with a specific property over recent years, following the home itself rather than just the current owner.
A roof over 15-20 years old can raise your premium by 20%-50% or more compared to a newer roof, and some insurers may limit coverage options for older roofs entirely.
It follows the property. This means a previous owner’s claims can appear on your home’s CLUE report and potentially affect your quotes, even though you didn’t file those claims yourself.
Homes farther from fire protection resources generally face higher potential losses in a fire, which insurers factor into pricing, particularly in rural areas.
Yes, often. Monitored security systems, updated electrical wiring, and other safety features can qualify for specific discounts that lower your overall premium.
Yes, typically. Swimming pools add a specific liability risk factor that most insurers account for in their pricing, sometimes alongside additional liability coverage recommendations.
Yes, some insurers apply specific risk weightings or exclusions for certain dog breeds considered higher risk for liability claims, which can affect both pricing and eligibility.
Request the property’s CLUE report as part of your home-buying due diligence, which can reveal claims history you wouldn’t otherwise know about from a previous owner.
If your roof is significantly aged, replacing it can meaningfully lower your premium and may also expand your insurer options, though it’s a substantial upfront cost to weigh against the savings.
This article is for informational purposes only. Always consult a licensed insurance professional before making coverage decisions. Trust My Policy does not sell insurance products or represent any insurer.

Jagadeesh Gutha is the founder of TrustMyPolicy.com, an independent insurance information platform covering life, health, car, home, and business insurance for US and UK readers. He researches insurance products, policy structures, and consumer rights to help everyday people make informed coverage decisions without the jargon. All content on TrustMyPolicy is independently researched, fact-checked, and written to educate — not to sell.
Insurance Guides for UK, USA & Worldwide We are not an insurer or broker.
Reader Comments (0)