
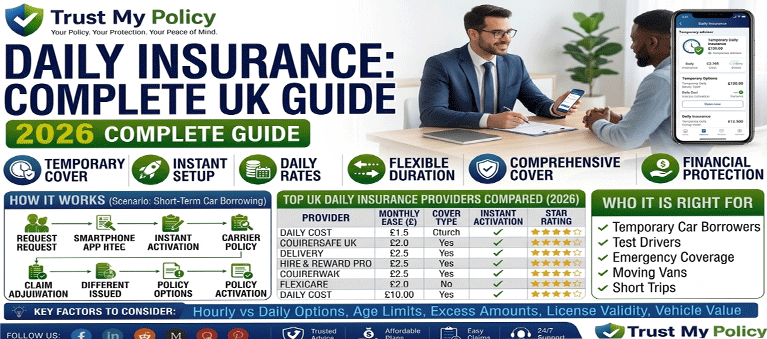
Daily insurance is a 24-hour, fully comprehensive motor policy you buy in your own name for one UK driving day. It suits occasional drivers borrowing or testing a car. In 2026 it costs roughly £12 to £50, with a median of £19.35 on Briefly (June 2026). The owner’s no-claims discount is not affected.
Sam, a 26-year-old teacher from Birmingham, needed his dad’s car to collect a sofa 90 miles away. His dad’s annual policy did not list him as a driver. A named-driver quote for the full year came to £340. Sam bought a 24-hour policy online in a few minutes instead. It cost £21, and his dad’s no-claims discount stayed untouched. This is an illustrative example built on 2026 price data.
Daily insurance in 2026 costs roughly £12 to £50 for 24 hours of fully comprehensive UK car cover. Briefly reported a median one-day price of £19.35 in June 2026. Veygo advertises one-day cover from £13.76 for learners and from £16.09 for full licence holders (Veygo, April 2026). This guide is updated for November 2026. Your daily insurance policy is separate from the car owner’s policy, so their no-claims discount is protected (RAC, 2026).
This guide shows what daily insurance covers, how it works and what it costs. You will see three types of daily insurance, a break-even calculator against weekly and annual cover, four scenarios, five costly mistakes and 13 answered questions. After reading, you will know exactly which daily insurance product to buy, or whether to skip it.
| Feature | Details |
| What it is | A 24-hour motor policy in your own name, separate from the car owner’s annual policy |
| Who needs it | Borrowers, learners practising privately, drivers collecting a newly bought car, and one-off business users |
| Typical cost | £12 to £50 per day; median £19.35 (Briefly, June 2026); from £16.09 for full licence holders (Veygo, April 2026) |
| Coverage included | Fully comprehensive as standard: accident damage, third-party liability, fire and theft |
| Key benefit | The car owner’s no-claims discount is not affected (RAC, 2026) |
| Key limitation | Cover outside the UK is typically third-party only unless you add EU cover (GoShorty, 2026) |
| Cover lengths | From 1 hour up to 28 days (Quotezone, 2026) |
| Regulated by | Financial Conduct Authority (FCA); cover must meet the Road Traffic Act 1988 |
Daily insurance is a short-term policy that covers you for 24 hours, and in the UK it usually means fully comprehensive car cover. Most people search for it when one day of driving puts them in a tight spot. The usual causes are a borrowed car, a newly bought car or a learner practice session.
Veygo describes daily insurance as a 24-hour block of fully comprehensive cover for day trips, test drives or emergency vehicle use. You choose the start time, pay online and receive your documents straight away.
Think of it as a day pass at a climbing wall. An annual policy is the yearly membership. Each visit costs more with a day pass, but you only pay on the days you climb.
Typical buyers include students driving home for the holidays, new drivers aged 17 to 25 who borrow a parent’s car, and tradespeople who need a one-off van for a job. Quotezone also lists daily insurance for vans, motorbikes and motorhomes, plus companies that need one-day business use on a car.
The phrase covers three different products, so pick the right one before you buy:
Daily car insurance. A 24-hour comprehensive motor policy for a specific car. Cuvva, Veygo, GoShorty and Briefly all sell it.
Daily car hire excess insurance. A separate policy that refunds the excess if a hire car is damaged. TravelSupermarket’s partner iCarhireinsurance.com sells it from £3.49 per day.
Pay-as-you-go cover. Annual policies that charge by the mile, such as By Miles, suit drivers who cover under 5,000 miles a year (Kaeltripton, April 2026).
Daily insurance works in five steps, from a quote to the moment cover ends. Most buyers finish the whole process in a few minutes.
The best daily insurance depends on what you need to cover: a driver, a hire car or a low-mileage car. This table compares the three types side by side.
| Criteria | Daily car insurance | Daily hire excess insurance | Pay-per-mile insurance |
| Cost | £12 to £50 per day; median £19.35 (Briefly, June 2026) | From £3.49 per day for UK residents aged 30 to 85 renting in Europe for 10+ days (iCarhireinsurance.com, 2026) | Base premium plus about 2p to 10p per mile (Kaeltripton, April 2026) |
| Coverage | Fully comprehensive for 24 hours on one car | Refunds the excess if the hire car is damaged | Standard annual cover billed by actual miles driven |
| Best for | Borrowing, test drives and learners | Holiday car hire | Second cars and drivers under 5,000 miles a year |
| Pros | Instant, flexible and protects the owner’s no-claims discount | Hire desks can charge up to £20 per day for their own excess cover | Cheaper than annual cover at low mileage |
| Cons | Costs far more per day than annual cover | Not a motor policy; it covers only the excess | Above 7,000 to 8,000 miles a year, standard cover is usually cheaper |
| Winner | Occasional drivers needing a car for 1 to 5 days | Anyone hiring a car abroad for 5 to 12 days a year | Owners who drive little but every week |
Winner: Daily car insurance, because it is the only one of the three that makes you legal to drive someone else’s car today.
We recommend daily car insurance for most readers because it solves the most common problem, which is driving a car you do not own for a short time.
The four scenarios below are illustrative. Names are invented, and prices use the 2026 figures cited in this guide.
Scenario 1: Sam, 26, teacher, Birmingham — borrowing a parent’s car
Sam needed his dad’s car for one day. An illustrative named-driver quote for the year came to £340. A one-day policy in his own name cost £21, so Sam saved £319. His dad’s no-claims discount stayed protected because the policies are separate. Verdict: buy a one-day policy in your own name for a single trip, and keep the named-driver route for regular use.
Scenario 2: Maya, 18, sixth-form student, Leeds — learner practice
Maya practises in her mum’s car on four Sundays this month. A learner daily policy at an illustrative £19 a day costs £76 in total, and Veygo advertises learner cover from £13.76. Cuvva says daily cover can cost less than adding a learner to an existing policy. Her supervisor must be 21 or over and have held a full licence for three years. Verdict: price daily learner cover first, and ask for a named-driver quote only if she practises weekly.
Scenario 3: Lena, 31, marketing manager, Bristol — a 10-day hire car in Spain
The hire desk offered its own excess waiver at up to £20 a day, which is £200 over ten days. Independent daily excess cover costs from £3.49 a day, or £34.90 for ten days, a saving of up to £165.10. TravelSupermarket warns you cannot backdate a policy bought after pick-up. Verdict: buy daily excess cover before you fly. Annual cover at £41.99 beats the daily rate from the 13th rental day in a year, because 12 days cost £41.88.
Scenario 4: Dan, 45, freelance editor, Leeds — a second car driven 70 days a year
Dan works from home and drives about 4,000 miles a year. He counted 70 driving days. At the £19.35 median, daily policies would cost £1,354.50. A standard annual policy might cost £600 to £800 (Kaeltripton, April 2026). Pay-per-mile cover is cheaper still for drivers under 5,000 miles. Verdict: daily insurance is the wrong tool for regular driving, and Dan should price pay-per-mile or a low-mileage annual policy.
| Pros | Cons |
| You get fully comprehensive cover for exactly the 24 hours you need. | You pay far more per day than on an annual policy. |
| The car owner’s no-claims discount is not affected by your policy. | A daily policy does not build a no-claims discount of its own. |
| You can buy cover in minutes and choose the start time. | Cover outside the UK is typically third-party only unless you add EU cover. |
| You avoid the cost of being added to someone else’s annual policy. | Back-to-back daily policies become expensive after about six days. |
| Providers sell cover for cars, vans, motorbikes and motorhomes. | Age, licence length and vehicle value rules can exclude some drivers. |
Mistake 1: Assuming the owner’s policy covers you
Why it happens: people think comprehensive cover follows the car. What to do instead: check the policy schedule, or buy your own daily insurance before you turn the key.
Mistake 2: Buying a string of daily policies for a long trip
Why it happens: each quote looks cheap on its own. What to do instead: compare a weekly policy once you need about six days. At £19.35 a day, six days cost £116.10 against around £110 for a week (carinsuranceexpert.co.uk, 2026).
Mistake 3: Choosing the wrong start time
Why it happens: buyers click “start now” and then leave hours later. What to do instead: schedule the start about 30 minutes before you plan to leave, and note the exact end time.
Mistake 4: Taking a UK policy into Europe unchecked
Why it happens: drivers assume a comprehensive policy travels. What to do instead: GoShorty says cover is typically third-party only outside the UK, and Cuvva sells EU cover as an extra. Confirm the territory before you cross.
Mistake 5: Paying the hire desk for excess cover at up to £20 a day
Why it happens: the desk offers it at the counter. What to do instead: buy independent daily excess cover in advance. It starts from £3.49 a day (iCarhireinsurance.com, 2026).
| ⚠️ Warning: Driving without insurance — a £300 penalty and 6 points
If you drive without valid insurance, GOV.UK rules set a £300 fixed penalty and 6 penalty points, and the car can be seized. New drivers can lose their licence after six points in the first two years. What to do instead: buy daily insurance before you drive. It costs a fraction of the penalty, and cover can start within minutes. |
Buy daily insurance if you need a car for one to five days and do not own it. Skip it if you drive regularly. Use this table to decide.
| Your situation | Our recommendation |
| Borrowing a friend’s or relative’s car once | ✅ Yes — buy daily insurance in your own name |
| Needing cover for 4 to 7 days | ✅ Compare — price a weekly policy; it can be cheaper from about six days |
| Driving the same car every week | ❌ No — ask for a named-driver or annual quote instead |
| Learner practising privately now and then | ✅ Yes — price daily learner cover first (from £13.76 at Veygo) |
| Hiring a car abroad for about 10 days | ✅ Yes — buy daily excess cover (from £3.49 a day) before you travel |
| Renting cars for 13+ days a year | ❌ No — annual excess cover (from £41.99 for Europe) is cheaper |
| Driving your own car under 5,000 miles a year | ❌ No — price pay-per-mile or a low-mileage annual policy |
| Driving for business on one day only | ✅ Yes — choose a provider offering one-day business use and declare it |
| 💡 Tip: The break-even rule
Divide the annual quote by £19.35. A £600 policy equals about 31 days of daily insurance and £800 equals about 41 days. Needing cover on fewer days than that makes a daily policy the cheaper choice. |
Daily insurance costs £12 to £50 for a day, and the median buyer pays about £19. Compare any quote against these 2026 figures.
| Scenario | Typical cost | Notes |
| Cheapest option: learner one-day policy (Veygo) | From £13.76 per day | 10th percentile price across 3,333 policies (Veygo, April 2026) |
| Cheapest option on Briefly | £12.20 per day | 10th percentile of customers (Briefly, June 2026) |
| Full licence one-day policy (Veygo) | From £16.09 per day | Advertised from-price (Veygo, April 2026) |
| Median Briefly customer | £19.35 per day | 50% paid this or less (Briefly, June 2026) |
| Median Covertime customer | £26.81 per day | January to June 2026 (Covertime) |
| Most expensive option: young or high-risk drivers | Up to £50 per day | Upper end of the 2026 range (carinsuranceexpert.co.uk) |
| Seven-day policy | About £110 (£15.71 a day) | Weekly cover beats daily cover after about six days (carinsuranceexpert.co.uk, 2026) |
| 28-day policy | About £340 (£12.14 a day) | The longest standard short-term cover (carinsuranceexpert.co.uk, 2026) |
| Hire car daily excess cover | From £3.49 per day | UK residents aged 30 to 85, Europe, 10+ days (iCarhireinsurance.com, 2026) |
Veygo, Cuvva, GoShorty and Briefly are the main UK providers of daily insurance. Ratings below include only figures we could verify. Check each live Trustpilot score before you buy.
Veygo — best overall
Why recommended: it is part of the Admiral Group, advertises full licence one-day cover from £16.09 and learner cover from £13.76, and holds 4.6 out of 5 on Trustpilot from 11,053 reviews (Veygo, 2026). Cost: from £13.76 to £16.09 per day, as advertised. Best for: learners and drivers who want an established insurer behind the policy.
Cuvva — best app experience
Why recommended: Cuvva says it has sold 13 million+ policies and serves 1 million+ drivers, with temporary cover from 1 hour and optional 1-day EU cover. Cost: published from-price around £18.14 per day. Best for: drivers who want the fastest app-based purchase. Rating: check the live Trustpilot score before buying.
GoShorty — best for flexible lengths
Why recommended: it sells hourly, daily, weekly and monthly cover, extendable to 28 days, with quotes in under two minutes. Cost: from about £20 per day. Best for: buyers who are unsure how many days they need. Rating: check the live Trustpilot score before buying.
Briefly — best published pricing data
Why recommended: it publishes real customer prices, with a median of £19.35 and a cheapest 10% at £12.20 (June 2026). Cost: £12.20 to £19.35 for most customers. Best for: price-sensitive drivers who want a realistic benchmark. Rating: check the live Trustpilot score before buying.
We recommend Veygo as the best overall for most readers because it combines Admiral backing, a verified 4.6 Trustpilot score from 11,053 reviews and the lowest advertised from-prices for both learners and full licence holders. Compare it with at least one other quote before you pay.
Daily insurance is a short-term policy that covers you for 24 hours, usually to drive a car in the UK. You buy it online in your own name, and it is separate from the car owner’s annual policy. Most one-day policies are fully comprehensive, and Cuvva, Veygo and GoShorty all sell them.
A day of cover costs roughly £12 to £50 in 2026, depending on your age, licence and car. Briefly reported a median of £19.35 in June 2026, and Veygo advertises full licence cover from £16.09. Younger drivers sit at the top of the range.
A one-day policy is cheaper when you drive the car on only a few days a year. Get a named-driver quote and divide it by £19.35 to find your break-even number of days. Cuvva also says daily cover for a learner can cost less than adding them to an existing policy.
Yes, you can buy daily insurance for a car you do not own. You need the registration number and the owner’s permission. The policy is in your name, and the owner’s no-claims discount is protected (GoShorty and RAC, 2026).
No, because your daily policy is separate from the owner’s policy. RAC states the owner’s No Claims Discount will not be affected. A claim on your policy is recorded against you instead.
You can usually get daily insurance within minutes. GoShorty says its quote takes under two minutes, and Veygo says cover starts whenever you choose. Have your licence details and the car’s registration ready.
A weekly policy usually becomes cheaper at about six days. At the £19.35 Briefly median, six days cost £116.10, while a seven-day policy was around £110 (carinsuranceexpert.co.uk, 2026). Prices vary by driver, so compare both quotes for your dates.
You may not need a daily motor policy for a hire car, but you may want daily excess insurance. Hire desks can charge as much as £20 a day for their own excess cover (TravelSupermarket). Independent daily excess cover starts from £3.49 a day for UK residents aged 30 to 85 renting in Europe for ten days or more.
A daily policy is worth it only if you need cover on few days a year. At £19.35 a day, 31 days cost about £600, the low end of an illustrative £600 to £800 annual policy (Kaeltripton, April 2026). Beyond that, annual or pay-per-mile cover is cheaper.
Cuvva, Veygo, GoShorty, Briefly and Dayinsure all sell daily insurance. Veygo is part of the Admiral Group and holds 4.6 out of 5 on Trustpilot from 11,053 reviews. Comparison sites such as Quotezone also list one-day quotes from several specialist insurers.
It costs more per day because providers price your exact day, car and licence, and you pay for flexibility and instant cover. A £19.35 median day compares with roughly £1.64 to £2.19 a day on a £600 to £800 annual policy. That gap is the price of buying only the days you need.
Not always. GoShorty says daily cover is typically third-party only outside the UK, while Cuvva offers 1-day EU cover as an option. Check the policy schedule for the countries and cover level before you travel.
Yes. Quotezone lists daily insurance options for cars, vans, motorbikes and motorhomes in the UK. Check each provider’s eligibility rules, because vehicle type, value and age limits vary.
This guide reflects the latest 2026 insurance data and provider information.
This article is for informational purposes only. Always consult a licensed insurance professional before making coverage decisions. Trust My Policy does not sell insurance products or represent any insurer.

Jagadeesh Gutha is the founder of TrustMyPolicy.com, an independent insurance information platform covering life, health, car, home, and business insurance for US and UK readers. He researches insurance products, policy structures, and consumer rights to help everyday people make informed coverage decisions without the jargon. All content on TrustMyPolicy is independently researched, fact-checked, and written to educate — not to sell.
Insurance Guides for UK, USA & Worldwide We are not an insurer or broker.
Reader Comments (0)